
Business line of credit lending USA programs give small business owners a flexible way to access working capital without committing to a rigid, lump-sum loan. Instead of borrowing one large amount, a business draws funds as needed, repays them, and borrows again, which makes this type of financing especially useful for managing payroll, inventory, or seasonal cash flow gaps. Nationwide lenders, including USA Patriot Loans, have made this type of funding faster and more accessible for established businesses generating at least $20,000 in monthly revenue.
Direct Answer: Business line of credit lending USA refers to revolving credit products offered by banks and alternative lenders that let qualified businesses draw, repay, and reuse funds up to an approved limit, typically ranging from $30,000 to $20 million. Approval generally depends on monthly revenue, time in business, and credit history rather than collateral alone.
What Is Business Line of Credit Lending USA?
Business line of credit lending USA is a form of revolving financing that allows a business to borrow up to a predetermined limit, repay what it uses, and draw again without reapplying. In other words, it functions similarly to a credit card but typically carries lower rates and higher limits designed for business operations.
Unlike a traditional term loan, interest usually accrues only on the amount drawn, not the full approved limit. Consequently, a business line of credit tends to be a more cost-efficient option for recurring or unpredictable expenses such as covering a slow sales month or purchasing inventory ahead of a busy season.
According to the U.S. Small Business Administration, access to working capital remains one of the top challenges reported by small business owners nationwide. As a result, flexible credit products like revolving lines have become an increasingly popular alternative to conventional bank loans.
Reviewing financing options is the first step toward securing business line of credit lending USA approval.
How Small Business Credit Line Financing Works Nationwide
Nationwide lenders evaluate applications based on several key factors, including monthly revenue, time in business, and personal or business credit history. Specifically, most alternative lenders prioritize cash flow over collateral, which allows businesses without significant assets to still qualify.
Once approved, funds become available through an online portal or direct transfer, and the business can draw any amount up to the approved limit. Repayments then restore available credit, creating a reusable funding source rather than a one-time disbursement.
For businesses weighing their options, understanding how to choose between a business line of credit and a term loan can clarify which structure best fits ongoing versus one-time funding needs.
Business Line of Credit vs. Term Loans: Which Fits Your Business?
A term loan delivers a lump sum upfront, repaid over a fixed schedule with set payments. In contrast, a line of credit offers ongoing access to capital, making it better suited for recurring expenses like payroll, supplies, or short-term cash flow dips.
Businesses planning a large, one-time investment, such as equipment financing or a major expansion, may still benefit more from a term loan. However, businesses that need flexibility for variable or seasonal costs often find a revolving line more practical overall.
Step-by-Step Guide to Securing a Business Credit Line
Applying for financing can feel overwhelming without a clear process. Therefore, following a structured approach helps business owners avoid delays and improve approval odds.
- Check your business eligibility. Review your average monthly revenue, time in business, and personal credit score to confirm you meet the minimum requirements most lenders expect before applying.
- Gather financial documentation. Collect recent bank statements, tax returns, and proof of revenue so the lender can verify your business income quickly and avoid processing delays.
- Compare lenders and terms. Evaluate multiple nationwide lenders based on interest rates, draw fees, credit limits, and funding speed before committing to any single offer.
- Submit your application. Complete the online application with accurate business details and upload your supporting documents to begin the underwriting and approval process.
- Review and accept your offer. Carefully read the repayment terms, fees, and draw limits in your approval offer, then accept the terms that best match your working capital needs.
For a more detailed walkthrough, this step-by-step guide to getting a line of credit for your small business breaks down each stage in greater depth.
Completing an online application is often the fastest path to approval for a business credit line.
Business Line of Credit Lending USA: Rates, Terms, and Qualifications
Rates and terms for business line of credit lending USA vary widely depending on the lender, loan amount, and the applicant’s financial profile. Generally, businesses with stronger revenue and longer operating history receive lower rates and higher credit limits.
Most lenders require at least $20,000 in average monthly revenue, along with several months of consistent business banking history. In addition, some lenders request a personal guarantee, particularly for newer businesses without extensive credit history.
Funding amounts commonly range from $30,000 to $20 million, with same-day or next-day funding available for qualified applicants. According to data referenced by the Federal Reserve’s Small Business Credit Survey, a significant share of small firms cite funding speed as a top priority when choosing a lender.
Why Businesses Choose USA Patriot Loans for Nationwide Credit Line Financing
USA Patriot Loans is a disabled-veteran-owned business financing company founded in November 2023, headquartered in Pennsylvania and serving businesses in all 50 states. The company focuses on helping established small and medium-sized businesses access $30,000 to $20 million in working capital without the long delays often associated with traditional bank underwriting.
Beyond business lines of credit, the company also offers SBA loans, term loans, equipment financing, invoice financing, and emergency business funding for businesses facing urgent cash flow needs. For businesses facing a sudden shortfall, this overview of how USA Patriot Loans can help with emergency business funding explains available options in more detail.
To learn more about the company’s lending philosophy and nationwide approach, visit the why choose us overview or explore current programs directly on usapatriotloans.com.
Common Mistakes to Avoid When Applying
One frequent mistake is underestimating how much funding a business actually needs, which can lead to repeated borrowing at higher costs. Similarly, submitting incomplete bank statements or tax documents often slows down underwriting unnecessarily.
Another common error involves accepting the first offer without comparing fee structures across lenders. For example, a slightly lower interest rate paired with high draw fees can end up costing more than a higher rate with minimal fees. Therefore, reviewing the full cost of capital, not just the headline rate, remains essential.
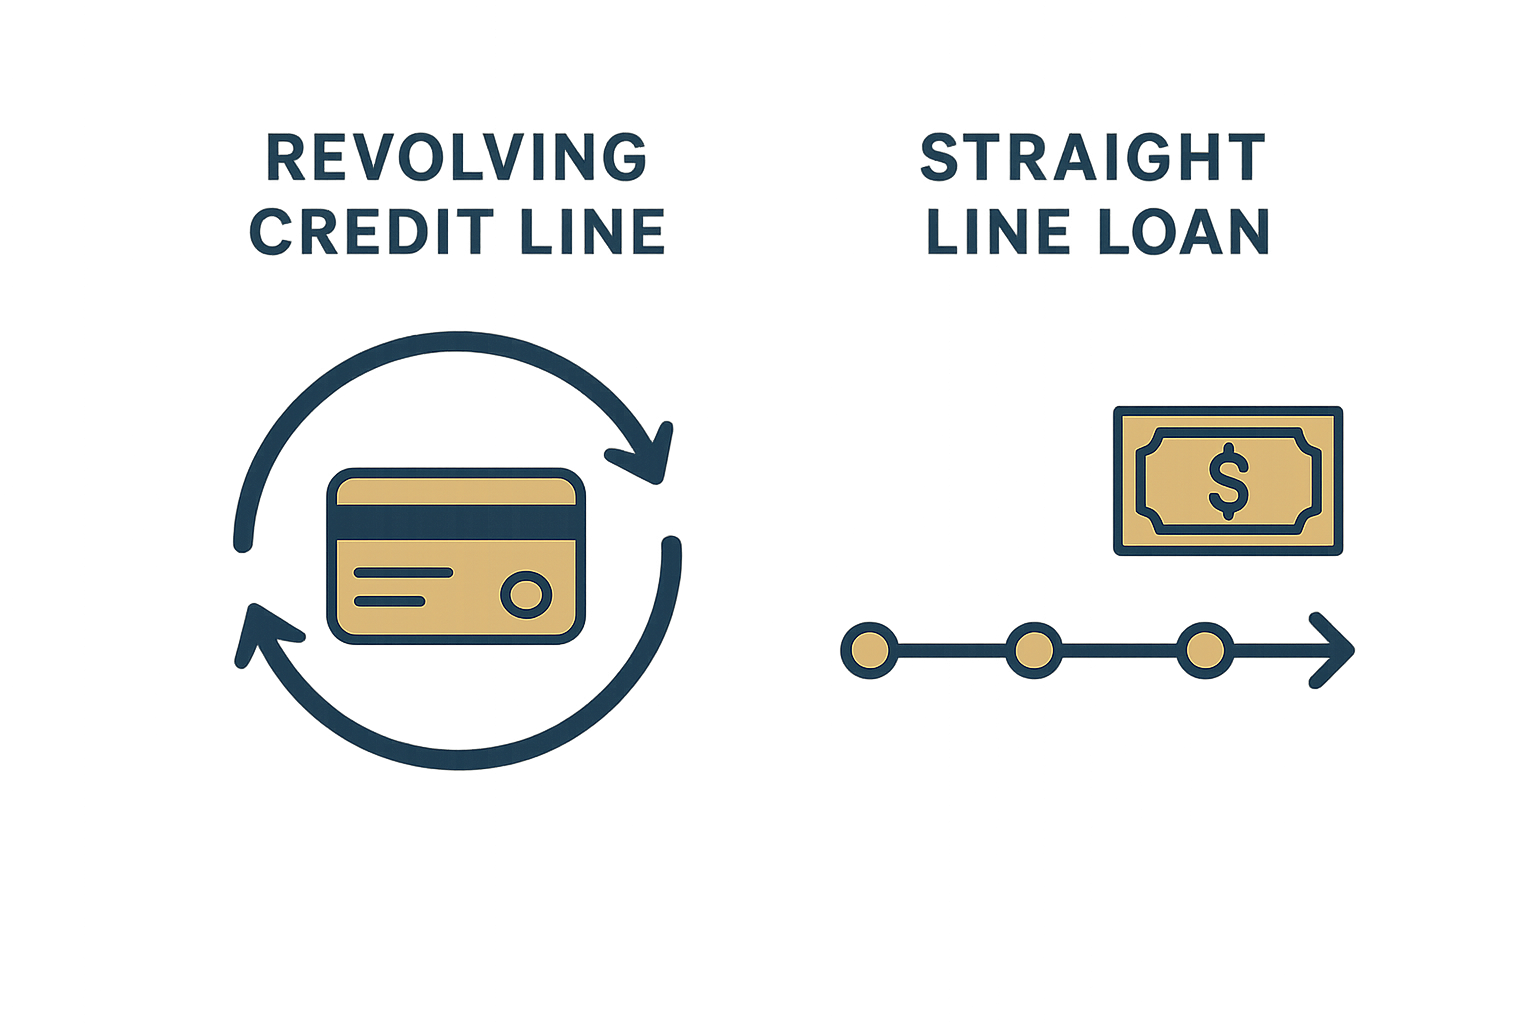
Revolving credit lines allow repeated draws, while term loans follow a fixed repayment path.
Frequently Asked Questions About Business Line of Credit Lending USA
What is a business line of credit?
A business line of credit is a revolving credit facility that lets a company draw funds up to a set limit, repay them, and borrow again. Unlike a term loan, you only pay interest on the amount you actually use.
How does business line of credit lending USA work for small businesses?
Business line of credit lending USA works by approving a business for a maximum credit limit based on revenue, time in business, and creditworthiness, then allowing draws as needed. As a result, businesses can manage cash flow gaps, cover payroll, or fund inventory without reapplying for a new loan each time.
What is the difference between a business line of credit and a business loan?
A term loan provides a lump sum repaid on a fixed schedule, while a line of credit is revolving and flexible. In contrast, a line of credit is better suited for ongoing or unpredictable expenses, whereas a term loan fits one-time, large purchases.
How much can I qualify for with a business line of credit?
Qualification amounts typically range from $30,000 to $20 million, depending on monthly revenue, business history, and documentation. Most lenders require at least $20,000 in average monthly revenue to consider an application.
How fast can I get approved for a business line of credit?
Many nationwide lenders, including alternative finance companies, can approve applications within 24 to 48 hours. Funding can often follow the same day once documents are verified.
What credit score do I need for a business line of credit?
Requirements vary, but many lenders accept personal credit scores starting around 600, especially when revenue and cash flow are strong. However, higher scores generally unlock lower rates and larger limits.
How much does a business line of credit cost?
Costs depend on the lender, loan amount, and risk profile, and may include interest rates, draw fees, or maintenance fees. Therefore, it is important to compare the total cost of capital rather than the interest rate alone.
What documents are required to apply for a business line of credit?
Lenders commonly request bank statements, tax returns, a business license, and proof of revenue. Additional documentation may include a profit and loss statement or accounts receivable aging report.
Can startups qualify for a business line of credit?
Most traditional lenders prefer at least six months to two years in business, though some alternative lenders work with younger companies that show strong revenue. Consequently, newer businesses may need to explore revenue-based financing first.
What are common mistakes business owners make when applying?
Common mistakes include underestimating funding needs, submitting incomplete documentation, and failing to compare multiple lenders. In addition, many owners overlook fee structures, which can significantly affect the true cost of borrowing.
Is a business line of credit better than a merchant cash advance?
A line of credit is generally more cost-effective and flexible than a merchant cash advance, which repays through a percentage of daily sales. Similarly, a line of credit allows reuse of funds without reapplying, unlike a one-time advance.
How do I choose the best lender for business line of credit lending USA?
Choosing the best lender for business line of credit lending USA involves comparing approval speed, funding limits, repayment terms, and customer support. Above all, look for a lender experienced in working with businesses similar in size and industry to your own.
Can I use a business line of credit for emergency funding?
Yes, a business line of credit is one of the most practical tools for emergency funding because funds are already approved and available on demand. This makes it faster than applying for new financing during a crisis.
What happens if I don’t use my entire credit line?
In most cases, you only pay interest or fees on the portion of the credit line you actually draw, not the full approved limit. Some lenders charge a small maintenance or inactivity fee, so it helps to confirm terms in advance.
Final Thoughts on Business Line of Credit Lending USA
Ultimately, business line of credit lending USA offers established businesses a flexible, reusable source of working capital that adapts to changing cash flow needs. Whether covering payroll during a slow month, stocking inventory ahead of peak season, or responding to an unexpected expense, a revolving credit line can provide faster and more adaptable access to funds than a traditional term loan.
Before applying, it helps to compare lenders, review documentation requirements, and understand the full cost of capital rather than focusing on rate alone. For businesses ready to explore options, USA Patriot Loans provides nationwide access to business lines of credit, term loans, and emergency funding designed for established small and medium-sized businesses across all 50 states.
Leave a Reply