
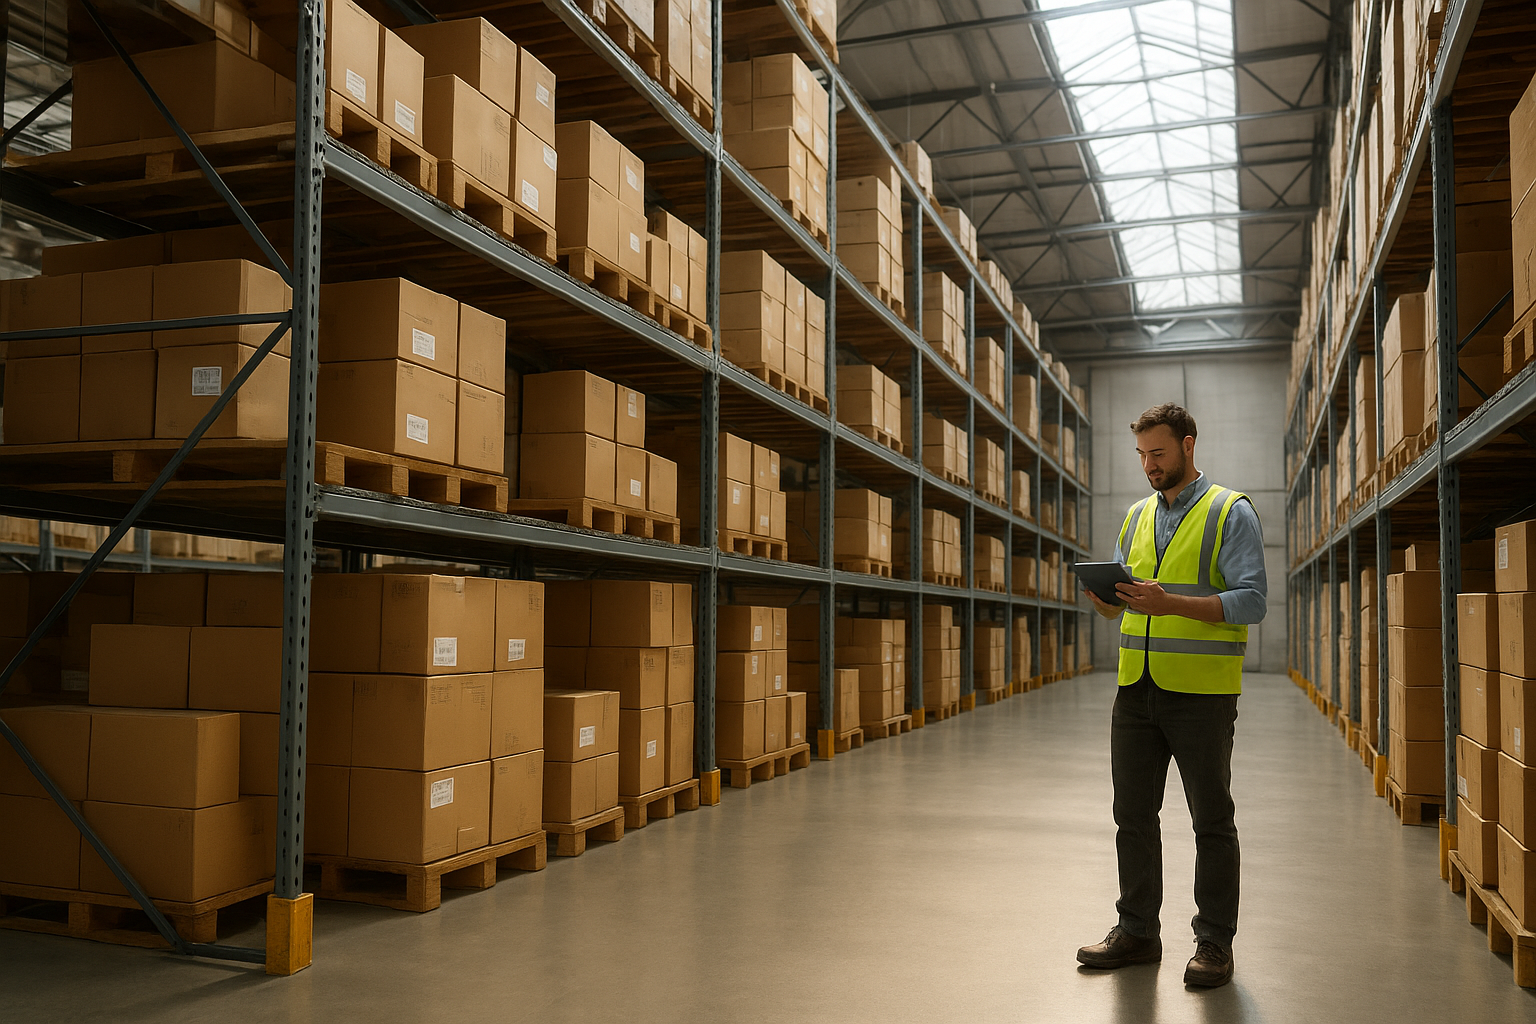
Inventory financing providers are lenders and finance companies that give businesses capital specifically to purchase stock, raw materials, or goods for resale, using that inventory as collateral. For growing retailers, wholesalers, and distributors, choosing the right provider can mean the difference between shelves that stay stocked and sales that slip away during peak demand.
Quick answer: Inventory financing providers advance funds against the value of a business’s stock, typically covering 50% to 80% of inventory value, so companies can buy goods now and repay as those goods sell. Rates, speed, and flexibility vary widely by lender, so comparing at least two or three options is essential.
What Are Inventory Financing Providers?
Inventory financing providers are companies that extend short-term or revolving credit tied directly to a business’s stock. Instead of evaluating only personal credit, these lenders look closely at the inventory itself, its resale value, turnover rate, and seasonality, to decide how much to advance.
This approach makes inventory financing especially useful for businesses that need to stock up ahead of a busy season but don’t want to tie up cash reserves. In addition, because the goods secure the loan, approval standards are often more flexible than unsecured lending options.
Inventory financing providers help businesses keep shelves stocked without draining working capital.
How Inventory Financing Works: A Step-by-Step Process
Understanding the funding process helps business owners move faster once they decide to apply. Below is the typical sequence used by most inventory financing lenders.
- Assess inventory value and funding need. Calculate the wholesale value of the inventory you need to purchase or already hold, since providers base loan amounts on a percentage of this figure rather than retail price.
- Gather financial and business documentation. Prepare recent bank statements, inventory reports, and revenue records so lenders can quickly verify cash flow and repayment ability during underwriting.
- Compare multiple inventory financing providers. Request quotes from at least two or three companies and compare advance rates, repayment schedules, and total borrowing costs before committing.
- Submit the application and inventory valuation. Completing the application with supporting valuation documents typically speeds up approval, since the collateral value directly determines the funding amount.
- Review terms and accept funding. Carefully review repayment terms, interest structure, and fees before signing, then receive funds, often within a few business days of final approval.
According to the Federal Reserve’s Small Business Credit Survey, roughly 65% of small businesses that sought financing in recent years cited cash flow gaps as a primary reason for applying, underscoring why timely inventory funding matters so much for day-to-day operations. You can review broader small business lending trends through the Federal Reserve’s small business survey data.
Types of Inventory Financing Companies
Not all inventory financing companies operate the same way. Some specialize in retail goods, while others focus on manufacturing components or seasonal merchandise. Recognizing the differences helps narrow down the right fit.
- Traditional bank lenders: Often offer lower rates but require strong credit history and longer approval timelines.
- Alternative finance companies: Provide faster decisions and more flexible underwriting, though typically at a higher cost of capital.
- SBA-backed lenders: Offer government-guaranteed loan programs that can include working capital for inventory, usually with longer terms and competitive rates. The U.S. Small Business Administration outlines eligibility requirements for these programs.
- Asset-based lenders: Focus heavily on collateral value rather than credit score, making them accessible to businesses with thinner credit files.
Businesses evaluating equipment purchase financing alongside inventory needs often find that pairing the two funding types strategically reduces overall borrowing costs.
How to Choose the Right Inventory Financing Lender for Your Business
Selecting among inventory financing lenders requires more than comparing headline rates. Above all, business owners should weigh how funding speed, repayment structure, and lender flexibility align with their sales cycles.
First, consider how quickly you need funds. If a seasonal rush is approaching, a lender offering same-day or near-instant decisions matters more than saving a percentage point on rate. Similarly, businesses with fluctuating cash flow should prioritize providers offering flexible repayment tied to sales rather than fixed monthly installments.
USA Patriot Loans, a nationwide, disabled-veteran-owned business financing company founded in 2023, works with established businesses generating at least $20,000 in monthly revenue and offers inventory financing alongside working capital loans, business lines of credit, and equipment financing ranging from $30,000 to $20 million. Because the company evaluates applications based on overall business performance rather than rigid credit thresholds alone, it can serve as one practical option for business owners comparing providers nationwide. You can review current programs directly at USA Patriot Loans.
Comparing multiple inventory financing providers helps business owners find better rates and repayment flexibility.
Costs, Rates, and Terms From Inventory Funding Providers
Cost structures vary significantly among inventory funding providers. Some charge a flat fee per advance, while others use factor rates or annual percentage rates depending on the loan structure. Consequently, comparing the total repayment amount, not just the headline rate, gives a clearer picture.
Typical advance rates range from 50% to 80% of inventory value, and repayment terms often run three to eighteen months. Businesses with strong sell-through history and established supplier relationships generally receive more favorable terms. For businesses also managing outstanding customer invoices, pairing inventory funding with invoice financing solutions can smooth cash flow on both ends of the sales cycle.
For a deeper look at how collateral-based lending is structured across industries, the Investopedia overview of inventory financing offers useful background context.
Common Mistakes to Avoid With Inventory Financing
Even well-intentioned borrowers stumble when working with inventory financing companies. Recognizing these pitfalls in advance can prevent costly setbacks.
One frequent mistake is over-borrowing based on optimistic sales projections rather than historical data, which strains repayment when demand falls short. Another common error is failing to shop around; accepting the first offer without comparing terms often means missing better rates elsewhere. Additionally, some businesses overlook how financing decisions for inventory interact with other funding needs, such as marketing expense financing or equipment upgrades, leading to fragmented debt structures that are harder to manage.
Businesses expanding equipment alongside inventory should also review how equipment financing works to avoid duplicating collateral commitments across multiple lenders.
Reviewing rate charts side by side helps identify which inventory financing companies offer the best value.
Frequently Asked Questions About Inventory Financing Providers
What are inventory financing providers?
Inventory financing providers are lenders or finance companies that give businesses capital specifically to purchase stock, raw materials, or goods for resale. The inventory itself typically serves as collateral for the loan.
How does inventory financing work?
A business applies for funding based on the value of existing or incoming inventory, and the lender advances a percentage of that value. Repayment usually happens as the inventory sells or on a fixed monthly schedule.
How much can I borrow from inventory financing companies?
Loan amounts commonly range from $30,000 to several million dollars, depending on the value of your inventory and overall business revenue. Larger, established businesses with strong sales history typically qualify for higher limits.
What credit score do inventory financing lenders require?
Many inventory financing lenders accept credit scores in the mid-600s because the inventory collateral reduces their risk. Businesses with stronger revenue and cash flow often receive better terms regardless of credit score.
How fast can I get funded by inventory financing providers?
Many providers fund approved applications within 3 to 7 business days, and some same-day funding options exist for qualified businesses. Speed depends on how quickly documentation, such as inventory valuations, is submitted.
What is the difference between inventory financing and a merchant cash advance?
Inventory financing is tied directly to the value of goods purchased and usually carries lower costs, while a merchant cash advance is repaid from future card sales at a higher effective rate. Inventory financing is generally better suited for businesses buying large stock orders.
Do inventory financing providers require collateral besides inventory?
In most cases, the inventory being purchased or held serves as the primary collateral, so additional collateral is often not required. Some lenders may still request a personal guarantee or a blanket lien for added security.
What industries commonly use inventory financing?
Retailers, wholesalers, distributors, and manufacturers rely on inventory financing most often because their businesses depend on holding significant stock. Seasonal businesses also use it to prepare for demand spikes.
What are common mistakes businesses make with inventory financing?
A common mistake is borrowing more than sales projections support, which leads to repayment strain. Another mistake is failing to compare multiple inventory financing providers before signing, missing better rates or terms elsewhere.
Are there alternatives to inventory financing?
Alternatives include working capital loans, business lines of credit, and invoice financing, each suited to different cash flow needs. Choosing the right option depends on whether the funding gap is tied to inventory purchases or broader operating expenses.
Can startups qualify with inventory financing companies?
Most inventory financing companies prefer businesses with at least six months of operating history and consistent monthly revenue. Startups without sales history may need to explore other funding sources first.
How do I choose the best inventory financing provider for my business?
Compare funding speed, cost of capital, repayment flexibility, and whether the lender understands your industry’s inventory cycles. Reading the fee structure closely and asking about early repayment penalties also helps identify the right fit.
Final Thoughts on Choosing Inventory Financing Providers
Ultimately, inventory financing providers give businesses a practical way to keep shelves stocked without exhausting cash reserves. As a result, comparing advance rates, repayment terms, and funding speed across several lenders remains the most reliable way to secure a deal that fits your sales cycle.
Whether you choose a traditional bank, an SBA-backed program, or a nationwide alternative lender, the right inventory financing provider should align with how your business actually sells and restocks goods. For businesses ready to explore options tailored to their revenue and growth stage, reviewing programs through a resource like USA Patriot Loans is a reasonable next step before committing to any single lender.