Category: Uncategorized

  • Business Expansion Financing Options Guide for 2026

    Business Expansion Financing Options Guide for 2026

    Business Expansion Financing Options Guide for 2026

    Business expansion financing options are the funding tools established business owners use to grow operations, open new locations, hire staff, or buy equipment without draining cash reserves. Whether you need $30,000 or $20 million, choosing the right path matters more than most owners realize. In addition, many business owners don’t know how many paths exist beyond a traditional bank loan. This guide walks through the most common business expansion financing options available nationwide, explains how each one works, and helps you decide which fits your company’s revenue, timeline, and growth goals.

    Quick Answer: Business expansion financing options include SBA loans, term loans, business lines of credit, equipment financing, invoice financing, and revenue-based financing. The best choice depends on how much capital you need, how fast you need it, and whether the expense is a one-time project or an ongoing operating cost.

    What Are Business Expansion Financing Options?

    Business expansion financing options are financial products earmarked specifically for growth projects rather than everyday operating expenses. Unlike a standard working capital loan, expansion financing is typically tied to a defined outcome, such as a new location, a large equipment purchase, or a hiring push. As a result, lenders often ask how the funds will be used before approving terms.

    Established businesses generating at least $20,000 in monthly revenue generally qualify for several of these products. For example, USA Patriot Loans works with owners nationwide to match them with financing ranging from $30,000 to $20 million based on revenue and time in business.
    Business owner reviewing business expansion financing options on a laptop

    Comparing business expansion financing options side by side helps owners choose the right fit for their growth plan.

    Top Types of Financing for Business Growth

    Several products fall under the umbrella of growth funding, and each works a little differently. Consequently, it helps to understand the basics before applying.

    • SBA loans — government-backed loans with lower rates and longer terms, ideal for large projects.
    • Term loans — a lump sum repaid over a fixed schedule, useful for one-time purchases.
    • Business lines of credit — revolving access to funds for ongoing or unpredictable costs.
    • Equipment financing — funding secured by the equipment itself, often with faster approval.
    • Revenue-based financing — repayment tied to a percentage of monthly sales.

    For a deeper side-by-side comparison, review this breakdown of the best options for expanding your business with loans, which covers rates and qualification details for each product.

    SBA Loans: A Popular Growth Funding Option

    SBA loans remain one of the most requested growth funding options because the Small Business Administration guarantees a portion of the loan, which lowers risk for lenders and often results in better rates for borrowers. According to the U.S. Small Business Administration, SBA 7(a) loans can fund up to $5 million and are frequently used for expansion, real estate, and equipment purchases.

    However, SBA loans involve more paperwork and a longer underwriting timeline than alternative lenders. Therefore, they tend to suit owners planning several months ahead rather than those needing emergency expansion capital.

    Working Capital and Lines of Credit for Expansion

    A business line of credit offers revolving access to capital, meaning you only pay interest on what you draw. This structure suits expansion projects with rolling costs, such as staggered inventory orders or phased renovations. Investopedia notes that a line of credit functions similarly to a credit card but typically carries lower rates and higher limits for businesses.

    In contrast, a term loan delivers one lump sum upfront, which works better for a single, clearly defined expansion cost like buying out a competitor’s lease or launching a second location.
    Upward trending growth chart representing small business revenue after securing expansion funding

    Steady revenue growth often follows a well-matched financing choice for business expansion.

    Equipment and Inventory Financing Explained

    Equipment financing lets a business purchase machinery, vehicles, or technology while using the asset itself as collateral. As a result, approval is often faster and rates can be lower than unsecured products. Similarly, inventory financing advances capital against stock a business plans to sell, which helps retailers and distributors restock ahead of busy seasons without tying up cash reserves.

    Both products work well alongside other business expansion financing options, since many owners combine a term loan for real estate with equipment financing for machinery in the same growth phase.

    How to Apply for Business Expansion Financing Options

    Applying for growth capital follows a fairly consistent process across most lenders. Specifically, the steps below outline what to expect from start to funding.

    1. Define your expansion goal, whether that means opening a location, buying equipment, hiring staff, or increasing inventory.
    2. Gather recent bank statements, tax returns, and profit and loss statements so lenders can evaluate your cash flow quickly.
    3. Compare SBA loans, lines of credit, term loans, and revenue-based financing against your projected repayment ability.
    4. Submit your application with accurate details and complete documentation to avoid underwriting delays.
    5. Review the final rate, term, and fees on any offer, then sign and prepare to deploy the funds.

    Owners who need capital quickly can also explore options that get capital in as little as 24 to 48 hours, which is often faster than traditional bank underwriting allows.

    Choosing the Right Expansion Financing Option for Your Business

    Selecting among business expansion financing options starts with an honest look at your timeline and repayment capacity. For instance, a business expecting steady, predictable sales growth might comfortably handle a fixed-term loan, while a business with seasonal swings may prefer a flexible line of credit instead.

    Data backs up the importance of planning ahead. The Federal Reserve’s Small Business Credit Survey has repeatedly found that a large share of small employer firms apply for financing specifically to pursue expansion or new business opportunities, not just to cover shortfalls. This suggests that proactive growth funding, rather than reactive borrowing, tends to produce better outcomes.

    For additional guidance on matching products to your situation, this capital finance guide and this resource on how to get funded fast break down qualification timelines in more detail.
    Lender and small business owner reviewing loan documents for expansion financing

    A signed agreement marks the final step after comparing business expansion financing options.

    Frequently Asked Questions About Business Expansion Financing Options

    What are business expansion financing options?

    Business expansion financing options are funding products, such as SBA loans, term loans, lines of credit, and revenue-based financing, built specifically to help established businesses grow rather than cover routine operating costs.

    How much can a business borrow for expansion?

    Most lenders, including USA Patriot Loans, fund anywhere from $30,000 to $20 million depending on revenue, time in business, and the financing type chosen.

    How fast can a business get approved for expansion funding?

    Alternative lenders often approve and fund applications within 24 to 48 hours, while SBA loans typically take several weeks due to additional underwriting steps.

    What credit score is needed to qualify for business expansion financing?

    Requirements vary by product, but many lenders accept scores in the mid-600s, and some revenue-based options weigh cash flow more heavily than personal credit.

    Is an SBA loan better than a business line of credit for growth?

    SBA loans generally offer lower rates and longer terms for large, one-time projects, while lines of credit suit recurring or unpredictable expansion costs that change month to month.

    What documents do lenders require for expansion financing?

    Lenders typically request bank statements, tax returns, a profit and loss statement, and a short explanation of how the funds will support growth.

    How much does business expansion financing cost?

    Costs vary widely by product; SBA loans often carry single-digit annual rates, while short-term or revenue-based financing carries higher factor rates in exchange for speed and flexibility.

    Can a merchant cash advance fund business expansion?

    Yes, a merchant cash advance can fund expansion quickly, though it generally suits shorter-term needs rather than large capital projects due to its repayment structure.

    What is the difference between equipment financing and a term loan?

    Equipment financing is secured by the purchased equipment itself, often allowing lower rates, while a term loan provides general-purpose capital without tying funds to a specific asset.

    What mistakes should business owners avoid when seeking expansion capital?

    Common mistakes include borrowing more than the growth plan requires, ignoring the total repayment cost, and failing to compare multiple business expansion financing options before committing.

    How long does it take to repay business expansion financing?

    Repayment terms range from a few months for short-term products to 10 or more years for certain SBA real estate loans, depending on the structure chosen.

    Who typically qualifies for business expansion financing options?

    Most lenders look for established businesses generating at least $20,000 in monthly revenue with an operating history of six months to two years or more.

    In summary, business expansion financing options give growing companies a practical way to fund new locations, equipment, staff, and inventory without exhausting cash reserves. From SBA loans to lines of credit and revenue-based financing, the right choice ultimately depends on your timeline, revenue, and growth plan. Above all, comparing multiple business expansion financing options before applying helps ensure you secure terms that actually fit your business, rather than settling for the first offer available.
  • Hard Money Commercial Loans for Businesses: 2026 Guide

    Hard Money Commercial Loans for Businesses: 2026 Guide

    Hard Money Commercial Loans for Businesses: 2026 Guide

    Hard money commercial loans for businesses give owners a way to access fast, asset-based financing when traditional banks move too slowly or say no outright. Unlike conventional bank loans, these loans rely primarily on the value of real estate or other business assets rather than credit scores or years of tax returns. Consequently, for business owners facing a time-sensitive opportunity or an urgent cash flow gap, hard money commercial loans for businesses can bridge the gap in days rather than months.

    Quick Answer: Hard money commercial loans for businesses are short-term, asset-secured loans funded by private lenders, usually closing in 5 to 15 business days. They suit businesses that have valuable collateral but cannot meet a bank’s credit, time-in-business, or paperwork requirements.

    What Are Hard Money Commercial Loans for Businesses?

    Hard money commercial loans for businesses are financing tools secured by hard assets, most often commercial real estate, rather than by the borrower’s creditworthiness alone. In practice, this means a private lender evaluates the property’s value, the loan-to-value ratio, and the business’s exit strategy far more closely than it examines tax returns or personal credit scores.

    Because the collateral carries most of the risk, approval timelines shrink dramatically. As a resource on hard money lending explains, these loans originated in real estate investing but have since expanded into broader commercial financing, including equipment purchases and business expansion. Therefore, a company that owns or is purchasing a warehouse, office building, or retail space can often use that asset to secure capital even when its financial statements would not satisfy a bank underwriter.

    Business owner reviewing hard money commercial loans for businesses paperwork in a modern office

    Reviewing hard money commercial loans for businesses often takes far less paperwork than a bank application.

    How Hard Money Business Loans Differ From Traditional Bank Financing

    Traditional bank loans emphasize credit history, cash flow documentation, and lengthy underwriting reviews that can stretch two to three months. In contrast, hard money business loans prioritize the collateral itself, which allows lenders to make faster decisions. For example, a bank might require two years of tax returns, audited financials, and a personal guarantee review, while a hard money lender may only need an appraisal and proof of ownership.

    This speed comes with a tradeoff, however. Interest rates on hard money financing typically run higher than bank rates, reflecting the increased risk private lenders accept. In addition, loan terms are usually shorter, often ranging from six months to three years, since hard money is designed as bridge financing rather than a long-term solution. Business owners exploring broader options can review the small business loan funding guide to compare traditional and alternative paths side by side.

    Who Benefits Most From Commercial Hard Money Loans

    Commercial hard money loans tend to fit specific situations rather than everyday operating needs. Real estate investors flipping a commercial property, businesses bridging a gap between a property sale and purchase, and companies that need to close quickly on an opportunity all commonly turn to this financing type. Similarly, businesses with blemished credit but substantial equity in owned property often find hard money loans more accessible than bank credit lines.

    On the other hand, businesses with strong financials and more time to wait should generally compare costs first. According to the Federal Reserve’s 2023 Small Business Credit Survey, nearly half of small employer firms that sought financing turned to online or alternative lenders, and speed was cited as a top reason for that choice. This pattern underscores why hard money remains popular even at a premium price, particularly for businesses in regions with tight real estate markets, such as those detailed in the hard money lending guide for Florida.

    Lender and small business owner shaking hands near a commercial property used as loan collateral

    A finalized agreement often follows a straightforward collateral review rather than a lengthy bank process.

    How the Hard Money Loan Process Works: A Step-by-Step Guide

    Understanding the mechanics of hard money commercial loans for businesses helps owners prepare faster and avoid delays. The process generally follows five steps:

    1. Identify eligible collateral. Determine which commercial property, equipment, or other business asset you can pledge, since the loan amount and approval odds depend heavily on the asset’s appraised value.
    2. Request a valuation. Order or gather a recent appraisal so the lender can quickly confirm the loan-to-value ratio and calculate the maximum amount they are willing to lend against your collateral.
    3. Submit a streamlined application. Provide basic business financials, ownership documents, and identification; hard money applications require far less paperwork than a traditional bank loan submission.
    4. Review loan terms and costs. Carefully compare the interest rate, origination fees, repayment term, and any prepayment penalties before accepting the lender’s offer to avoid unexpected costs later.
    5. Close and receive funding. Once documents are signed and collateral is verified, funds are typically disbursed within one to three weeks, giving the business fast access to working capital.

    Notably, businesses that need capital even faster than this timeline allows may want to explore options outlined in the guide on getting capital in 24 to 48 hours, which covers alternative products built for same-day or next-day funding needs.

    Hard Money Loan Rates, Terms, and Costs to Expect

    Pricing on hard money commercial financing varies by lender, collateral quality, and loan-to-value ratio. That said, most borrowers can expect the following general ranges:

    Factor Typical Range
    Interest rate 8% to 15%
    Loan term 6 months to 3 years
    Loan-to-value ratio 50% to 75%
    Funding timeline 5 to 15 business days

    In addition to interest, most lenders charge origination fees ranging from 1% to 5% of the loan amount. As a result, calculating the total cost of capital, not just the headline rate, is essential before signing. For a broader view of how the Small Business Administration defines and structures lending programs, the SBA’s loan program overview offers useful context on how alternative financing compares to government-backed options.

    Common Mistakes to Avoid With Hard Money Commercial Financing

    Even though hard money commercial financing moves quickly, rushing the decision can create problems later. Below are mistakes business owners frequently make:

    • Borrowing without a clear plan to repay or refinance before the term ends.
    • Focusing only on the interest rate while ignoring origination fees and penalties.
    • Overestimating the collateral’s value, which can reduce the approved loan amount.
    • Failing to compare multiple lenders before accepting the first offer received.

    Similarly, businesses facing an unexpected cash shortfall sometimes choose hard money financing without exploring faster, lower-cost emergency alternatives first. Reviewing how emergency business funding options work can help determine whether hard money is truly the best fit for a given situation.

    Clock and calendar graphic illustrating a fast funding timeline for hard money business loans

    Speed is the primary advantage of hard money commercial loans for businesses compared with bank financing.

    Is a Hard Money Commercial Loan Right for Your Business?

    Deciding whether this financing fits your business depends largely on timeline, collateral, and cost tolerance. If a business owns valuable real estate or equipment and needs funding faster than a bank can deliver, hard money commercial loans for businesses often make sense. However, if time is less pressing and credit qualifications are strong, a lower-cost option such as a term loan or line of credit may be more economical.

    Above all, matching the financing product to the specific need matters more than chasing the lowest advertised rate. Companies nationwide, including those served by USA Patriot Loans, typically evaluate several financing types side by side before committing, since the right structure depends on revenue, collateral, and how quickly funds are needed.

    Frequently Asked Questions About Hard Money Commercial Loans for Businesses

    What are hard money commercial loans for businesses?

    Hard money commercial loans for businesses are short-term, asset-backed loans secured primarily by real estate or other business assets rather than credit history or tax returns. They are issued by private lenders and designed to close quickly, often within one to three weeks.

    How fast can a business get funded with a hard money commercial loan?

    Most hard money commercial loans fund within 5 to 15 business days, compared to 60 to 90 days for a conventional bank loan. Speed comes from the lender’s focus on collateral value rather than extensive financial underwriting.

    What credit score do I need to qualify for a hard money business loan?

    Many hard money lenders will consider borrowers with credit scores in the 550 to 600 range because the loan is secured by collateral. That said, a stronger credit profile can still help secure better rates and terms.

    How much can a business borrow through hard money commercial financing?

    Loan amounts typically range from $30,000 to $20 million, depending on the appraised value of the collateral and the lender’s loan-to-value limits. Larger loans usually require commercial real estate as security.

    What collateral is required for commercial hard money loans?

    Commercial hard money loans are most often secured by commercial real estate, such as office buildings, warehouses, or retail space. Some lenders also accept equipment or other high-value business assets.

    How do hard money loan rates compare to traditional bank loans?

    Hard money loan rates generally run higher than bank loans, often between 8% and 15%, because lenders take on more risk and move faster. In exchange, businesses skip the lengthy underwriting process banks require.

    What is the typical term length for a hard money commercial loan?

    Most hard money commercial loans run from 6 months to 3 years, making them a short-term bridge rather than a permanent financing solution. Businesses often refinance into longer-term debt once conditions improve.

    What are common mistakes businesses make with hard money commercial financing?

    A frequent mistake is borrowing without a clear exit strategy for repaying or refinancing the loan before the term ends. Other errors include underestimating total costs and failing to compare multiple lenders before signing.

    Can startups qualify for hard money business loans?

    Startups can qualify if they own or can pledge sufficient collateral, since approval depends more on asset value than years in business. However, most lenders still prefer at least some operating history and revenue.

    What documents are needed to apply for a hard money commercial loan?

    Applicants typically need proof of collateral ownership, a recent appraisal or valuation, basic business financials, and a government-issued ID. Requirements are far lighter than the paperwork a bank loan demands.

    Is a hard money loan the same as a merchant cash advance?

    No, a hard money loan is secured by collateral and repaid on a fixed schedule, while a merchant cash advance is repaid through a percentage of daily sales. They serve different needs and carry different cost structures.

    What happens if a business cannot repay a hard money commercial loan?

    If a business defaults, the lender can seize and sell the pledged collateral to recover the outstanding balance. This is why borrowers should only use hard money financing with a realistic repayment or refinancing plan.

    Final Thoughts on Hard Money Commercial Loans for Businesses

    In summary, hard money commercial loans for businesses offer a practical path to capital when speed matters more than the lowest possible rate. They work best for companies with valuable real estate or assets, a clear repayment plan, and a time-sensitive need that traditional banks cannot meet fast enough. Ultimately, comparing rates, terms, and lenders carefully, and weighing hard money against other financing options, helps ensure the chosen path supports the business’s growth rather than straining it. For businesses ready to explore whether this financing fits their situation, working with an experienced nationwide lender can simplify the comparison and speed up the decision.

  • Emergency Business Funding Solutions: Fast Capital Guide

    Emergency Business Funding Solutions: Fast Capital Guide

    Emergency Business Funding Solutions: Fast Capital Guide

    Emergency business funding solutions give small business owners fast access to cash when unexpected expenses, revenue gaps, or sudden opportunities can’t wait for traditional bank approval timelines. Whether a critical piece of equipment breaks down, payroll is due, or a vendor needs immediate payment, these financing options are built for speed rather than months of underwriting. However, the real challenge for many entrepreneurs isn’t knowing funding exists — it’s knowing where to find lenders who can actually deliver within days, not weeks.

    Quick Answer: Emergency business funding solutions are short-term financing products — including working capital loans, merchant cash advances, and business lines of credit — designed to deliver capital within 24 to 72 hours for urgent operational needs.

    In particular, business owners turn to these options when cash flow timing doesn’t match an urgent expense. As a result, lenders specializing in emergency funding have streamlined their application and approval processes specifically to close that gap. For a closer look at how a dedicated lender structures this process, here is how USA Patriot Loans helps businesses navigate emergency funding from application through payout.

    What Are Emergency Business Funding Solutions?

    Emergency business funding solutions are financing products specifically structured to address time-sensitive cash flow needs rather than long-term capital investments. Unlike a traditional SBA loan, which can take 30 to 90 days to fund, these solutions prioritize speed, often requiring far less documentation and faster underwriting decisions.

    Specifically, lenders in this space focus primarily on recent business bank statements and monthly revenue rather than years of tax returns or a flawless credit history. As a result, many businesses that wouldn’t yet qualify for conventional bank financing can still secure working capital quickly. According to the Federal Reserve’s Small Business Credit Survey, a majority of small firms report applying for financing specifically to cover operating expenses or address cash flow shortfalls, which underscores just how common the need for fast capital truly is. You can review traditional lending timelines directly through the U.S. Small Business Administration’s loan programs for comparison.

    Furthermore, emergency funding typically comes in amounts tailored to immediate needs, though some providers extend financing up to $20 million for larger operational emergencies, expansion-related cash crunches, or multi-location businesses facing simultaneous challenges.

    Why Businesses Need Fast Access to Working Capital

    Even well-managed, profitable companies rarely keep large cash reserves sitting idle. Instead, most revenue gets reinvested into inventory, payroll, or growth initiatives. Consequently, when an unexpected expense hits, a gap naturally forms between available cash and immediate obligations.

    Common triggers include equipment breakdowns, a sudden drop in receivables, seasonal slowdowns, or natural disasters that disrupt operations. In addition, some businesses need rapid capital not because of a crisis, but because of a time-sensitive opportunity, such as a bulk inventory discount or a lease renewal deadline. Either way, waiting weeks for approval simply isn’t practical. For businesses facing this exact scenario, quick funding options for equipment and payroll needs are specifically designed to close that timing gap without disrupting day-to-day operations.

    Small business owner reviewing emergency business funding solutions on a laptop

    Reviewing bank statements and revenue data is the first step toward securing emergency business funding solutions.

    Types of Urgent Business Financing Options

    Not every emergency calls for the same type of financing. Therefore, understanding the main categories helps business owners choose the option that fits both the urgency and the repayment ability of their company.

    Working Capital Loans

    These short-term loans provide a lump sum repaid over a fixed period, typically three to eighteen months. They work well for covering operating costs during a temporary revenue dip.

    Merchant Cash Advances

    A merchant cash advance exchanges a lump sum for a percentage of future sales, repaid through daily or weekly debits. Although approval is fast, the overall cost is often higher than other options, so it’s best reserved for genuinely urgent situations.

    Business Lines of Credit

    A business line of credit offers revolving access to funds, allowing a company to draw only what it needs and pay interest solely on the amount used. This flexibility makes it ideal for recurring or unpredictable emergencies.

    Other options worth considering include invoice financing, which advances cash against unpaid customer invoices, and equipment financing, which funds urgent equipment repairs or replacements. For a deeper comparison of these products, the complete guide to getting funded fast breaks down eligibility requirements for each type.

    How to Qualify for Rapid Business Funding

    Qualifying for emergency business funding solutions generally requires less paperwork than a bank loan, but following a clear process still improves approval odds and funding speed. Below is the typical sequence most lenders follow.

    1. Gather recent bank statements: Collect three to six months of business bank statements, since lenders use this to verify monthly revenue instead of requiring years of tax returns.
    2. Determine the funding amount needed: Calculate the exact dollar amount required to cover the emergency, whether it’s payroll, equipment repair, or an inventory shortfall, to avoid over-borrowing.
    3. Choose the right funding type: Select between a working capital loan, line of credit, merchant cash advance, or invoice financing based on repayment ability and urgency.
    4. Submit the application: Complete the lender’s application online or by phone, uploading bank statements and basic business formation documents for review.
    5. Review and accept the offer: Carefully review the factor rate or interest rate, repayment schedule, and total cost before signing any agreement.
    6. Receive funds via direct deposit: Once approved, funds are typically deposited directly into the business bank account within 24 to 48 hours of acceptance.

    Business owner completing an online application for fast emergency funding

    A streamlined application process is what allows emergency business funding solutions to move so quickly.

    How Quickly Can You Access Emergency Capital?

    Most emergency business loans fund within 24 to 48 hours of approval, and some same-day business funding products can deposit cash the same business day. However, timelines vary depending on how quickly documentation is submitted and how a lender verifies revenue.

    For instance, a line of credit may fund faster on repeat draws since the underwriting work was already completed during initial approval. In contrast, larger funding amounts above $1 million typically require additional review, even within an expedited process. To understand realistic timelines for different funding sizes, see this breakdown of how businesses secure capital in 24 to 48 hours.

    Choosing the Right Emergency Funding Partner

    Above all, speed shouldn’t come at the expense of transparency. A trustworthy lender clearly explains the total repayment amount, the repayment schedule, and any fees before a business owner signs an agreement.

    In addition, it helps to work with a lender that understands your specific industry and funding amount range, whether that’s $30,000 for a short-term gap or several million for a larger operational emergency. USA Patriot Loans, a disabled-veteran-owned business founded in 2023, works with established businesses nationwide generating at least $20,000 in monthly revenue, offering funding from $30,000 up to $20 million. You can review current options directly at usapatriotloans.com or explore this capital finance guide for funding a business fast to compare available structures.

    Common Mistakes to Avoid With Emergency Business Loans

    Even under time pressure, a few avoidable mistakes can cost businesses more than necessary. Specifically, applying with multiple lenders at once can trigger several hard credit inquiries without improving approval odds.

    Similarly, accepting the first offer without comparing total repayment cost often leads to overpaying for speed. Finally, waiting until a crisis becomes severe narrows available options and limits negotiating power. Instead, business owners should research funding sources before an emergency arises whenever possible, so they already know where to turn when timing matters most.

    Frequently Asked Questions About Emergency Business Funding Solutions

    What are emergency business funding solutions?

    Emergency business funding solutions are short-term financing products, such as working capital loans, merchant cash advances, and business lines of credit, built to deliver cash within 24 to 72 hours. They prioritize speed and minimal paperwork over the lengthy underwriting of traditional bank loans.

    How quickly can a business receive emergency funding?

    Many lenders can approve and fund applications within 24 to 48 hours once bank statements and basic business details are submitted. Same-day funding is sometimes available for businesses with strong, consistent revenue.

    What documents are required to apply for emergency business funding?

    Most lenders ask for three to six months of business bank statements, a government-issued ID, and basic business formation documents. Tax returns and collateral are sometimes requested for larger funding amounts, but they are rarely required for smaller, short-term requests.

    How much do emergency business loans typically cost?

    Costs vary by product and risk profile, with factor rates or interest rates generally higher than conventional bank loans because of the speed and reduced documentation involved. Businesses should always compare the total repayment amount, not just the headline rate, before accepting an offer.

    What is the difference between emergency funding and a traditional SBA loan?

    SBA loans are government-backed and typically take 30 to 90 days to fund because of extensive underwriting. Emergency funding options skip much of that process, trading slightly higher costs for approval and funding timelines measured in days rather than months.

    Can a business with bad credit qualify for emergency funding?

    Yes, many emergency funding providers weigh monthly revenue and cash flow more heavily than personal credit scores. A business generating consistent revenue of at least $20,000 per month can often qualify even with a less-than-perfect credit history.

    What is a merchant cash advance and how does it work?

    A merchant cash advance provides a lump sum in exchange for a percentage of future sales, repaid automatically through daily or weekly debits. It is not technically a loan, which allows for faster approval but typically results in a higher overall cost of capital.

    Why do businesses need emergency funding instead of relying on cash reserves?

    Even profitable businesses often keep limited cash reserves because capital is reinvested into payroll, inventory, or growth. When an unexpected expense arises, emergency funding bridges the gap without forcing owners to pause operations or delay payroll.

    What are common mistakes businesses make when seeking emergency funding?

    The most common mistakes include applying with multiple lenders simultaneously, accepting the first offer without comparing terms, and underestimating the total repayment cost. Businesses should also avoid waiting until a crisis is severe before exploring funding options.

    How much money can a business borrow in an emergency funding situation?

    Funding amounts generally range from $30,000 to $20 million depending on the lender, revenue, and the type of financing selected. Smaller short-term needs are typically funded on the lower end, while larger operational emergencies may qualify for higher amounts.

    What is the best practice for choosing an emergency funding lender?

    Compare total repayment cost, funding speed, and the lender’s transparency about fees before signing any agreement. It also helps to work with a lender experienced in your industry and willing to explain terms in plain language.

    How long does repayment take for emergency business loans?

    Repayment terms for short-term emergency products typically range from three months to 24 months, depending on the product and amount borrowed. Daily or weekly automatic payments are common for faster repayment structures like merchant cash advances.

    Final Thoughts on Emergency Business Funding Solutions

    In summary, emergency business funding solutions exist to close the gap between an urgent business need and the slow pace of traditional bank financing. From working capital loans and merchant cash advances to business lines of credit, each option offers a different balance of speed, cost, and repayment flexibility. Therefore, the right choice depends on how quickly cash is needed and how comfortably the business can manage repayment.

    Ultimately, preparing documentation in advance, comparing offers carefully, and working with a transparent lender makes the biggest difference when time is short. Businesses that understand these options before a crisis hits are far better positioned to act quickly when emergency business funding solutions become necessary.

  • Commercial Hard Money Loan Providers: How to Choose in 2026

    Commercial Hard Money Loan Providers: How to Choose in 2026

    Commercial Hard Money Loan Providers: How to Choose in 2026

    Commercial hard money loan providers offer asset-based financing that helps business owners secure funding quickly when traditional bank loans fall through. Unlike conventional lenders, these providers focus primarily on the value of collateral — usually commercial real estate — rather than relying solely on credit history or years in business. As a result, businesses facing tight timelines or unconventional financial profiles can still access the capital they need to close deals, renovate properties, or bridge short-term cash flow gaps. This guide explains how these lenders operate, what to expect in costs, and how to choose a reputable provider for your next commercial project.

    Quick answer: Commercial hard money loan providers are private lending companies that issue short-term, collateral-backed loans to businesses, typically closing in 7 to 14 days at interest rates between 8% and 15%. They are best suited for time-sensitive real estate deals, renovations, or situations where a bank has already declined financing.

    What Are Commercial Hard Money Loan Providers?

    Commercial hard money loan providers are private lenders or lending companies that issue short-term, asset-backed loans secured by commercial property or business assets. Because these loans emphasize collateral value over borrower credit, providers can approve and fund deals in days rather than the weeks or months typical of bank underwriting. This makes them a practical option for time-sensitive acquisitions, renovations, or bridge financing.

    In particular, these lenders serve businesses that own real estate, equipment, or inventory but do not fit the strict box required by conventional banks. Consequently, hard money financing has become a common tool for investors and operating companies alike who need capital fast and are willing to accept a higher rate in exchange for speed and flexibility.

    Commercial hard money loan providers reviewing property documents with a business owner

    Commercial hard money loan providers evaluate collateral value more than credit history.

    How Hard Money Loans Work for Business Owners

    Hard money loans work differently than standard bank financing because the collateral, not the borrower’s balance sheet, drives the approval decision. Typically, a lender orders an appraisal, confirms the loan-to-value ratio, and issues a term sheet within a day or two of receiving basic property information.

    Furthermore, because underwriting is streamlined, borrowers often skip the lengthy documentation cycles required by banks. However, this convenience comes at a price: rates are higher, terms are shorter, and most loans are structured to be repaid or refinanced within six months to three years.

    According to the Wikipedia overview of hard money lending, this financing category originated in real estate investing and has since expanded into broader commercial and business use cases where speed outweighs rate sensitivity.

    Key Features to Look for in Hard Money Lenders

    Not all hard money lenders operate the same way, so it helps to know what separates a reliable provider from a risky one. Above all, transparency about fees and realistic funding timelines are the strongest indicators of a trustworthy lender.

    • Clear loan-to-value guidelines stated upfront, typically 50–75% of collateral value.
    • Straightforward fee disclosure covering points, underwriting costs, and prepayment terms.
    • Proven funding track record with verifiable closed deals in your property type.
    • Direct communication from underwriters rather than layers of brokers.
    • Flexible terms for renovation draws, extensions, or interest-only periods.

    How to Choose Among Commercial Hard Money Loan Providers

    Choosing the right lender starts with comparing several commercial hard money loan providers side by side rather than accepting the first offer. Specifically, borrowers should request written term sheets so rates, points, and closing costs can be compared apples to apples.

    In addition, it is worth verifying how long the lender has operated, whether they fund loans directly or broker them out, and how they have handled extensions for past borrowers. For businesses that also need working capital, lines of credit, or SBA-backed options alongside hard money financing, reviewing a broader comparison of lenders for business loan approval nationwide can help clarify which financing mix fits your situation.

    Step-by-Step: How to Secure Funding From a Hard Money Lender

    Once you understand the landscape, following a consistent process makes it easier to move from application to closing without surprises.

    1. Evaluate your collateral and equity position. Calculate the current market value of your property or business assets and determine how much equity you can offer as security, since most lenders require equity cushions between 30 and 50 percent.
    2. Gather property and business documentation. Collect recent appraisals, title reports, rent rolls, financial statements, and a written exit strategy so lenders can quickly verify collateral value and repayment plans.
    3. Compare multiple commercial hard money loan providers. Request term sheets from at least three lenders and compare interest rates, points, loan-to-value ratios, and prepayment penalties, since terms vary widely between lenders.
    4. Submit your application and review terms. Submit the formal application with supporting documents, then carefully review the commitment letter for fees, timelines, and default provisions before signing anything.
    5. Close and receive funding. After the lender completes a property inspection and title search, most loans close within seven to fourteen days and deliver funds directly to your business.

    Small business owner closing a fast commercial hard money loan agreement

    Closing typically happens within one to two weeks once documentation is complete.

    What Do Commercial Hard Money Loans Cost?

    Commercial hard money loans typically carry interest rates between 8% and 15% annually, along with origination points of 1% to 5% of the loan amount. These figures are notably higher than bank rates, but they reflect the speed and flexibility borrowers gain in exchange.

    Meanwhile, the U.S. Small Business Administration notes that many small businesses struggle to meet bank underwriting standards, which helps explain why a meaningful share of owners eventually turn to alternative lenders such as hard money providers for time-sensitive needs. Since pricing varies by lender, always confirm whether points are charged upfront or rolled into the loan balance before signing.

    Commercial Hard Money Loans vs. Traditional Business Financing

    Compared with SBA loans or bank term loans, hard money financing trades a lower rate for speed and flexibility. Traditional lenders may take 60 to 90 days to fund, while hard money loans commonly close within two weeks.

    Therefore, many businesses use hard money as a bridge while arranging longer-term financing, or as a one-time solution for a deal that cannot wait for conventional approval. For a broader look at how fast-funding options compare across loan types, this guide to fast funding options for small companies outlines additional alternatives worth considering.

    Comparison illustration of commercial hard money loans versus traditional bank financing

    Commercial hard money loan providers prioritize speed, while banks prioritize rate.

    Where USA Patriot Loans Fits In

    USA Patriot Loans is a nationwide, disabled-veteran-owned business financing company founded in 2023 and headquartered in Pennsylvania, serving businesses across all 50 states. Among its offerings, the company provides commercial hard money loans alongside SBA loans, working capital loans, business lines of credit, equipment financing, and same-day business funding for companies generating at least $20,000 in monthly revenue.

    For business owners comparing options, reviewing USA Patriot Loans’ nationwide financing programs alongside other commercial hard money loan providers can help clarify which lender offers the right combination of speed, funding range, and loan structure for a specific property or working capital need. Businesses located in fast-growing real estate markets may also find this hard money lending guide for Florida businesses useful for state-specific considerations.

    Avoiding Common Pitfalls When Comparing Lenders

    Even experienced borrowers can overlook details that lead to costly surprises later. For instance, failing to confirm whether a lender funds loans directly or brokers them elsewhere can add unexpected delays right before closing.

    Similarly, borrowers sometimes underestimate prepayment penalties or extension fees, only to discover them after signing. As a result, reading every clause in the term sheet — and asking direct questions about worst-case scenarios — remains one of the best ways to avoid mistakes. Businesses exploring fast-approval alternatives alongside hard money financing may also benefit from this overview of business loans with fast approval.

    Frequently Asked Questions

    What is a commercial hard money loan?

    A commercial hard money loan is a short-term, asset-based loan secured primarily by commercial real estate or business collateral rather than by credit score alone. These loans are issued by private lenders and typically close much faster than conventional bank financing.

    How do commercial hard money loan providers determine loan amounts?

    Commercial hard money loan providers base loan amounts mainly on the appraised value of the collateral, usually lending between 50 and 75 percent of the property’s value. Borrower income and credit history play a smaller role than the strength of the underlying asset.

    Why do businesses choose hard money loans over bank loans?

    Businesses often choose hard money loans when speed matters more than rate, such as during a time-sensitive acquisition or when a bank has denied financing. Approval and funding can happen in days instead of the weeks or months banks typically require.

    How is a commercial hard money loan different from a traditional bank loan?

    Traditional bank loans emphasize credit history, tax returns, and lengthy underwriting, while hard money loans focus on collateral value and exit strategy. As a result, hard money financing carries higher rates but far fewer approval hurdles.

    How much do commercial hard money loans cost?

    Commercial hard money loans typically carry interest rates between 8 and 15 percent annually, plus origination points ranging from 1 to 5 percent of the loan amount. Exact pricing depends on the lender, loan-to-value ratio, and property type.

    How fast can commercial hard money loan providers fund a deal?

    Many commercial hard money loan providers can close a deal within 7 to 14 days once collateral documentation and title work are complete. This speed makes them a common choice for auctions, foreclosures, and other time-sensitive purchases.

    What credit score do you need for a commercial hard money loan?

    Most hard money lenders do not require a minimum credit score since the loan is secured by collateral, though some prefer a score above 600 for additional assurance. Strong equity in the property usually matters far more than the borrower’s credit profile.

    What types of properties qualify for commercial hard money financing?

    Eligible properties often include office buildings, retail centers, warehouses, multifamily buildings, and mixed-use developments. Some lenders also accept raw land or properties needing renovation, provided there is sufficient equity.

    What are common mistakes borrowers make when choosing hard money lenders?

    Common mistakes include failing to compare multiple term sheets, overlooking prepayment penalties, and not confirming the lender’s actual funding history. Borrowers should also avoid signing agreements without a clear exit strategy for repaying or refinancing the loan.

    What documents do commercial hard money loan providers require?

    Most commercial hard money loan providers request a property appraisal, title report, purchase agreement or rent roll, and a brief statement of the borrower’s exit strategy. Compared to bank underwriting, documentation requirements are typically much lighter.

    Can startups qualify for commercial hard money loans?

    Yes, startups can qualify since hard money lending emphasizes collateral value rather than years in business. However, most lenders still expect the business to generate meaningful revenue or hold significant equity in the pledged property.

    What happens if I can’t repay a commercial hard money loan on time?

    If a borrower cannot repay on schedule, most lenders offer an extension for an additional fee, though continued default can lead to foreclosure on the collateral. This is why having a clear exit strategy before closing is essential.

    Are commercial hard money loans regulated?

    Commercial hard money loans are subject to state lending laws and general consumer protection oversight, but they face fewer federal underwriting mandates than residential mortgages. Borrowers should still verify a lender’s licensing through resources such as the Consumer Financial Protection Bureau before signing any agreement.

    Final Thoughts

    Choosing among commercial hard money loan providers ultimately comes down to balancing speed against cost. In particular, borrowers who compare term sheets, verify a lender’s track record, and plan a clear exit strategy tend to avoid the most common pitfalls. Whether you need to close on a property in days or bridge a short-term cash flow gap, hard money financing remains a practical tool when used deliberately and with a firm repayment plan in place. Above all, take the time to compare reputable commercial hard money loan providers before committing, since the right lender can make the difference between a smooth closing and an expensive mistake.

  • Inventory Financing Providers: Top Options for 2026

    Inventory Financing Providers: Top Options for 2026

    Inventory Financing Providers: Top Options for 2026

    Inventory financing providers are lenders and finance companies that give businesses capital specifically to purchase stock, raw materials, or goods for resale, using that inventory as collateral. For growing retailers, wholesalers, and distributors, choosing the right provider can mean the difference between shelves that stay stocked and sales that slip away during peak demand.

    Quick answer: Inventory financing providers advance funds against the value of a business’s stock, typically covering 50% to 80% of inventory value, so companies can buy goods now and repay as those goods sell. Rates, speed, and flexibility vary widely by lender, so comparing at least two or three options is essential.

    What Are Inventory Financing Providers?

    Inventory financing providers are companies that extend short-term or revolving credit tied directly to a business’s stock. Instead of evaluating only personal credit, these lenders look closely at the inventory itself, its resale value, turnover rate, and seasonality, to decide how much to advance.

    This approach makes inventory financing especially useful for businesses that need to stock up ahead of a busy season but don’t want to tie up cash reserves. In addition, because the goods secure the loan, approval standards are often more flexible than unsecured lending options.

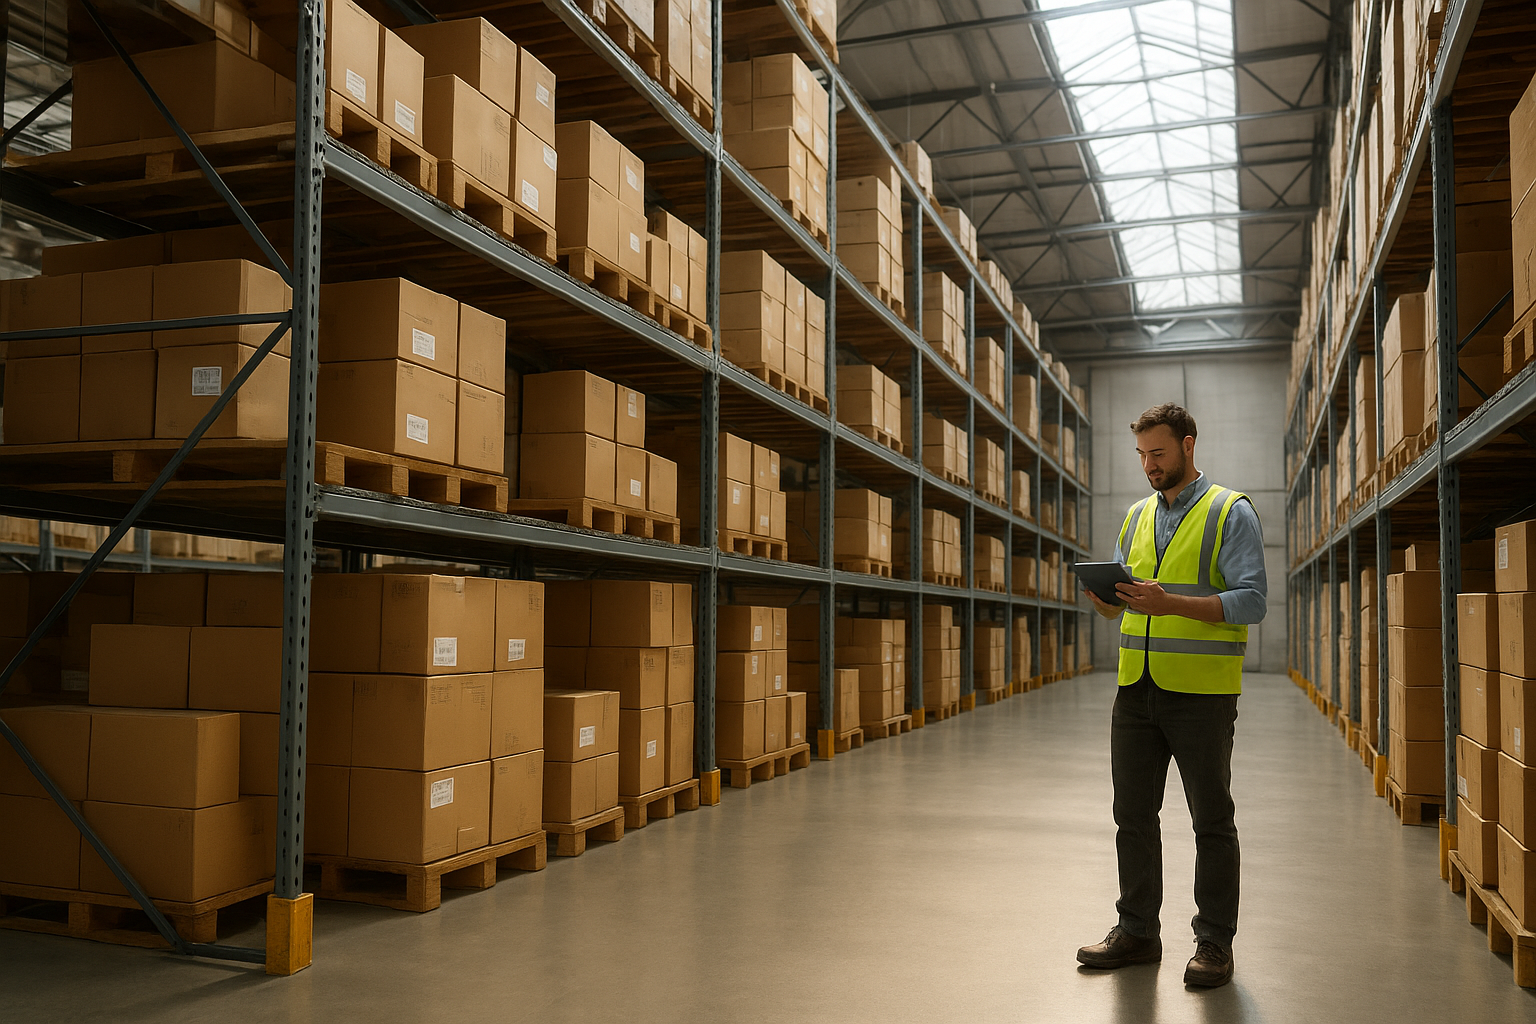
    Warehouse shelves stocked with boxed inventory representing funding from inventory financing providers

    Inventory financing providers help businesses keep shelves stocked without draining working capital.

    How Inventory Financing Works: A Step-by-Step Process

    Understanding the funding process helps business owners move faster once they decide to apply. Below is the typical sequence used by most inventory financing lenders.

    1. Assess inventory value and funding need. Calculate the wholesale value of the inventory you need to purchase or already hold, since providers base loan amounts on a percentage of this figure rather than retail price.
    2. Gather financial and business documentation. Prepare recent bank statements, inventory reports, and revenue records so lenders can quickly verify cash flow and repayment ability during underwriting.
    3. Compare multiple inventory financing providers. Request quotes from at least two or three companies and compare advance rates, repayment schedules, and total borrowing costs before committing.
    4. Submit the application and inventory valuation. Completing the application with supporting valuation documents typically speeds up approval, since the collateral value directly determines the funding amount.
    5. Review terms and accept funding. Carefully review repayment terms, interest structure, and fees before signing, then receive funds, often within a few business days of final approval.

    According to the Federal Reserve’s Small Business Credit Survey, roughly 65% of small businesses that sought financing in recent years cited cash flow gaps as a primary reason for applying, underscoring why timely inventory funding matters so much for day-to-day operations. You can review broader small business lending trends through the Federal Reserve’s small business survey data.

    Types of Inventory Financing Companies

    Not all inventory financing companies operate the same way. Some specialize in retail goods, while others focus on manufacturing components or seasonal merchandise. Recognizing the differences helps narrow down the right fit.

    • Traditional bank lenders: Often offer lower rates but require strong credit history and longer approval timelines.
    • Alternative finance companies: Provide faster decisions and more flexible underwriting, though typically at a higher cost of capital.
    • SBA-backed lenders: Offer government-guaranteed loan programs that can include working capital for inventory, usually with longer terms and competitive rates. The U.S. Small Business Administration outlines eligibility requirements for these programs.
    • Asset-based lenders: Focus heavily on collateral value rather than credit score, making them accessible to businesses with thinner credit files.

    Businesses evaluating equipment purchase financing alongside inventory needs often find that pairing the two funding types strategically reduces overall borrowing costs.

    How to Choose the Right Inventory Financing Lender for Your Business

    Selecting among inventory financing lenders requires more than comparing headline rates. Above all, business owners should weigh how funding speed, repayment structure, and lender flexibility align with their sales cycles.

    First, consider how quickly you need funds. If a seasonal rush is approaching, a lender offering same-day or near-instant decisions matters more than saving a percentage point on rate. Similarly, businesses with fluctuating cash flow should prioritize providers offering flexible repayment tied to sales rather than fixed monthly installments.

    USA Patriot Loans, a nationwide, disabled-veteran-owned business financing company founded in 2023, works with established businesses generating at least $20,000 in monthly revenue and offers inventory financing alongside working capital loans, business lines of credit, and equipment financing ranging from $30,000 to $20 million. Because the company evaluates applications based on overall business performance rather than rigid credit thresholds alone, it can serve as one practical option for business owners comparing providers nationwide. You can review current programs directly at USA Patriot Loans.

    Small business owner comparing loan offers from inventory financing providers on a laptop

    Comparing multiple inventory financing providers helps business owners find better rates and repayment flexibility.

    Costs, Rates, and Terms From Inventory Funding Providers

    Cost structures vary significantly among inventory funding providers. Some charge a flat fee per advance, while others use factor rates or annual percentage rates depending on the loan structure. Consequently, comparing the total repayment amount, not just the headline rate, gives a clearer picture.

    Typical advance rates range from 50% to 80% of inventory value, and repayment terms often run three to eighteen months. Businesses with strong sell-through history and established supplier relationships generally receive more favorable terms. For businesses also managing outstanding customer invoices, pairing inventory funding with invoice financing solutions can smooth cash flow on both ends of the sales cycle.

    For a deeper look at how collateral-based lending is structured across industries, the Investopedia overview of inventory financing offers useful background context.

    Common Mistakes to Avoid With Inventory Financing

    Even well-intentioned borrowers stumble when working with inventory financing companies. Recognizing these pitfalls in advance can prevent costly setbacks.

    One frequent mistake is over-borrowing based on optimistic sales projections rather than historical data, which strains repayment when demand falls short. Another common error is failing to shop around; accepting the first offer without comparing terms often means missing better rates elsewhere. Additionally, some businesses overlook how financing decisions for inventory interact with other funding needs, such as marketing expense financing or equipment upgrades, leading to fragmented debt structures that are harder to manage.

    Businesses expanding equipment alongside inventory should also review how equipment financing works to avoid duplicating collateral commitments across multiple lenders.

    Hands reviewing financing rate charts to compare terms from inventory financing companies

    Reviewing rate charts side by side helps identify which inventory financing companies offer the best value.

    Frequently Asked Questions About Inventory Financing Providers

    What are inventory financing providers?

    Inventory financing providers are lenders or finance companies that give businesses capital specifically to purchase stock, raw materials, or goods for resale. The inventory itself typically serves as collateral for the loan.

    How does inventory financing work?

    A business applies for funding based on the value of existing or incoming inventory, and the lender advances a percentage of that value. Repayment usually happens as the inventory sells or on a fixed monthly schedule.

    How much can I borrow from inventory financing companies?

    Loan amounts commonly range from $30,000 to several million dollars, depending on the value of your inventory and overall business revenue. Larger, established businesses with strong sales history typically qualify for higher limits.

    What credit score do inventory financing lenders require?

    Many inventory financing lenders accept credit scores in the mid-600s because the inventory collateral reduces their risk. Businesses with stronger revenue and cash flow often receive better terms regardless of credit score.

    How fast can I get funded by inventory financing providers?

    Many providers fund approved applications within 3 to 7 business days, and some same-day funding options exist for qualified businesses. Speed depends on how quickly documentation, such as inventory valuations, is submitted.

    What is the difference between inventory financing and a merchant cash advance?

    Inventory financing is tied directly to the value of goods purchased and usually carries lower costs, while a merchant cash advance is repaid from future card sales at a higher effective rate. Inventory financing is generally better suited for businesses buying large stock orders.

    Do inventory financing providers require collateral besides inventory?

    In most cases, the inventory being purchased or held serves as the primary collateral, so additional collateral is often not required. Some lenders may still request a personal guarantee or a blanket lien for added security.

    What industries commonly use inventory financing?

    Retailers, wholesalers, distributors, and manufacturers rely on inventory financing most often because their businesses depend on holding significant stock. Seasonal businesses also use it to prepare for demand spikes.

    What are common mistakes businesses make with inventory financing?

    A common mistake is borrowing more than sales projections support, which leads to repayment strain. Another mistake is failing to compare multiple inventory financing providers before signing, missing better rates or terms elsewhere.

    Are there alternatives to inventory financing?

    Alternatives include working capital loans, business lines of credit, and invoice financing, each suited to different cash flow needs. Choosing the right option depends on whether the funding gap is tied to inventory purchases or broader operating expenses.

    Can startups qualify with inventory financing companies?

    Most inventory financing companies prefer businesses with at least six months of operating history and consistent monthly revenue. Startups without sales history may need to explore other funding sources first.

    How do I choose the best inventory financing provider for my business?

    Compare funding speed, cost of capital, repayment flexibility, and whether the lender understands your industry’s inventory cycles. Reading the fee structure closely and asking about early repayment penalties also helps identify the right fit.

    Final Thoughts on Choosing Inventory Financing Providers

    Ultimately, inventory financing providers give businesses a practical way to keep shelves stocked without exhausting cash reserves. As a result, comparing advance rates, repayment terms, and funding speed across several lenders remains the most reliable way to secure a deal that fits your sales cycle.

    Whether you choose a traditional bank, an SBA-backed program, or a nationwide alternative lender, the right inventory financing provider should align with how your business actually sells and restocks goods. For businesses ready to explore options tailored to their revenue and growth stage, reviewing programs through a resource like USA Patriot Loans is a reasonable next step before committing to any single lender.

  • Business Expansion Loans Nationwide: Fast Funding Guide

    Business Expansion Loans Nationwide: Fast Funding Guide

    Business Expansion Loans Nationwide: Fast Funding Guide

    Business expansion loans nationwide give established companies the working capital they need to open new locations, buy equipment, or hire additional staff without waiting months for a decision. For small and mid-sized business owners across the United States, the right financing can turn a growth opportunity into a completed project instead of a missed one. This guide explains how nationwide expansion financing works, which loan types fit different growth goals, and how to choose a lender that can fund your business quickly.

    In short: Business expansion loans nationwide are financing products, including term loans, SBA loans, and working capital loans, that provide roughly $30,000 to $20 million in capital to help established businesses grow across state lines, with funding often available in days rather than months.

    Map illustration representing business expansion loans nationwide connecting businesses across the United States

    Business expansion loans nationwide connect growing companies in every state with the same fast funding process.

    What Are Business Expansion Loans Nationwide?

    Business expansion loans nationwide are financing solutions designed for established businesses that need capital to grow beyond their current location, market, or capacity. Unlike loans limited to regional banks, nationwide programs let business owners in any state apply through a single lender and receive funding regardless of geography. As a result, a bakery in Ohio and a logistics company in Texas can use the same lending process to access growth capital.

    These loans typically fund projects such as opening a second location, purchasing commercial real estate, upgrading equipment, or building inventory ahead of a busy season. Because lenders that operate nationwide serve thousands of businesses, they often build streamlined underwriting systems that can approve applications faster than a traditional community bank. In addition, many nationwide lenders offer multiple loan structures, from short-term working capital to longer SBA-backed term loans, so business owners can match financing to their specific expansion timeline.

    According to the U.S. Small Business Administration, there are more than 33 million small businesses operating in the United States, and access to capital remains one of the most common barriers to growth for this group. Nationwide lending has emerged partly to address that gap, giving business owners in smaller markets the same access to capital as those in major metro areas.

    How Nationwide Business Expansion Financing Works

    Nationwide business expansion financing generally follows a similar path regardless of which state a business operates in. Lenders review revenue, time in business, and cash flow rather than relying solely on personal credit history or local bank relationships.

    Most programs require that a business generate at least $20,000 in monthly revenue and have been operating for six months or longer, though requirements vary by lender and loan type. Furthermore, because underwriting is done digitally, business owners can often submit bank statements and receive a decision within one to two business days.

    Once approved, funding structures vary. Some loans distribute a lump sum with fixed weekly or monthly payments, while others, such as business lines of credit, allow owners to draw funds as needed and pay interest only on the amount used. Consequently, a business owner planning a phased expansion, such as renovating one location before opening a second, might prefer a line of credit over a single lump-sum loan. The Federal Reserve’s Small Business Credit Survey tracks how small businesses across the country use external financing, including for expansion purposes, and remains a useful resource for understanding broader borrowing trends.

    Types of Financing for Growing Businesses

    Not every expansion project calls for the same type of financing. The following options are among the most common nationwide funding tools available to established businesses:

    • SBA Loans: Government-backed loans with longer terms and competitive rates, suited for major expansion projects like real estate purchases.
    • Term Loans: Lump-sum financing repaid over a fixed schedule, ideal for one-time expansion costs.
    • Business Lines of Credit: Revolving credit that covers ongoing or unpredictable expansion expenses.
    • Equipment Financing: Funding tied to the purchase of machinery, vehicles, or technology needed for growth.
    • Working Capital Loans: Short-term funding that supports day-to-day operations during a growth phase.
    • Merchant Cash Advances: An advance against future card sales, repaid through a percentage of daily transactions (see this overview of merchant cash advances for more detail).
    • Revenue-Based Financing: Repayment tied directly to monthly revenue, which can ease cash flow pressure during slower months.
    • Invoice Financing: Converts unpaid invoices into immediate cash flow, useful for B2B companies expanding while waiting on client payments.

    Each option carries different costs and repayment structures. Therefore, reviewing the best options for expanding your business with loans before applying, rather than accepting the first offer, is one of the best ways to protect long-term cash flow while growing.

    Business owner reviewing expansion loan documents and approval details at an office desk

    Reviewing terms carefully before signing helps business owners choose the right financing structure.

    How to Qualify for Business Expansion Loans Nationwide

    Qualifying for business expansion loans nationwide depends more on business performance than on where the business is located. Most nationwide lenders look at monthly revenue, time in business, and recent bank statements rather than requiring extensive collateral.

    Common qualification benchmarks include:

    1. Monthly revenue of at least $20,000, verified through recent bank statements.
    2. A minimum of six months to one year in business operation.
    3. Consistent deposit activity showing stable or growing cash flow.
    4. No unresolved bankruptcies or active default on existing business debt.

    Because requirements differ by lender and loan type, business owners considering an SBA loan should expect a longer review process and more documentation than those applying for a short-term working capital loan. In contrast, alternative lenders that specialize in fast funding may approve applications with fewer documents, though often at a higher cost. For a closer look at how approval standards compare, this guide to the best lenders for business loan approval nationwide breaks down what underwriters typically require.

    Step-by-Step: Applying for Nationwide Expansion Funding

    Applying for nationwide business expansion loans generally follows the same core steps, regardless of the lender or loan type selected.

    1. Define the expansion goal. Determine exactly how the funds will be used, such as a new location, equipment, inventory, or working capital, since this shapes which loan type fits best.
    2. Gather financial documents. Collect three to six months of business bank statements, along with basic business formation documents and an estimate of monthly revenue.
    3. Compare lender options. Review at least two or three nationwide lenders to compare funding speed, repayment terms, and total borrowing cost before submitting an application.
    4. Submit the application. Complete the lender’s application, typically online, and provide requested documentation promptly to avoid delays during underwriting review.
    5. Review the offer carefully. Examine the repayment schedule, fees, and any prepayment terms before accepting funds, since these details affect the true cost of the loan.
    6. Receive funding and deploy capital. Once approved, funds are typically deposited directly into the business bank account, often within one to five business days depending on the lender.

    Choosing a Nationwide Business Lender You Can Trust

    Selecting the right lender matters as much as selecting the right loan type. Above all, business owners should look for transparent terms, a clear funding timeline, and a lender willing to explain the total cost of capital before any documents are signed.

    USA Patriot Loans, a disabled-veteran-owned business financing company headquartered in Pennsylvania, works with established businesses nationwide seeking $30,000 to $20 million in working capital or commercial financing. The company offers SBA loans, term loans, business lines of credit, equipment financing, and several other funding products designed to help businesses expand without the delays often associated with traditional bank lending.

    Business owners comparing options can review this nationwide comparison guide to small business lenders to see how funding speed and requirements differ by provider. Similarly, businesses facing a time-sensitive opportunity may benefit from understanding how USA Patriot Loans helps with emergency business funding when a growth window is closing quickly. For a broader overview of financing options suited to different growth stages, visit USA Patriot Loans directly to review current program details and eligibility requirements.

    New business location opening after securing nationwide expansion financing

    Nationwide expansion financing often helps businesses open new locations faster than traditional bank loans.

    Frequently Asked Questions About Business Expansion Loans Nationwide

    What are business expansion loans nationwide?

    Business expansion loans nationwide are financing products, such as term loans, SBA loans, and business lines of credit, that allow established businesses in any state to borrow between roughly $30,000 and $20 million to fund growth. They typically fund new locations, equipment, inventory, or working capital needs.

    How fast can I get approved for a business expansion loan?

    Many nationwide lenders can approve applications within one to two business days once bank statements and basic documentation are submitted. Funding can sometimes arrive within 24 to 48 hours after approval, depending on the lender and loan type.

    How much can I borrow for business expansion?

    Loan amounts generally range from $30,000 to $20 million, depending on monthly revenue, time in business, and the loan type selected. Larger amounts typically require stronger financials and are more common with SBA loans or term loans.

    What credit score is needed to qualify?

    Many alternative lenders focus more on revenue and cash flow than on personal credit score, though scores in the mid-600s or higher generally open up better rates. SBA loans and traditional bank financing usually require stronger credit profiles than short-term working capital products.

    What is the difference between a term loan and a business line of credit?

    A term loan provides a lump sum repaid on a fixed schedule, making it suited for one-time expansion costs. A business line of credit is revolving, letting a business draw funds as needed and pay interest only on the amount used.

    Can newer businesses qualify for expansion financing?

    Some nationwide lenders will consider businesses with as little as six months of operating history, provided revenue is consistent. Businesses under six months old typically have fewer options and may need to rely on equipment financing or invoice financing instead.

    What documents are required to apply?

    Most lenders request three to six months of business bank statements, basic formation documents, and an estimate of monthly revenue. SBA loans typically require additional paperwork, including tax returns and a formal business plan.

    Are SBA loans better than alternative lenders for expansion?

    SBA loans usually offer lower rates and longer terms, making them well suited for large, long-term projects like real estate purchases. Alternative lenders often approve faster and require less documentation, which can matter more when timing is critical.

    What is a common mistake business owners make when seeking expansion funding?

    One common mistake is accepting the first loan offer without comparing total borrowing cost across two or three lenders. Another is borrowing more than the expansion project actually requires, which increases repayment pressure unnecessarily.

    How long does it take to receive funds after approval?

    After approval, funds are often deposited within one to five business days, though some lenders offer same-day funding for qualified applicants. SBA loans typically take longer, often two to eight weeks from application to funding.

    Is collateral required for business expansion loans?

    Collateral requirements vary by loan type. SBA loans and larger term loans often require collateral or a personal guarantee, while many working capital loans and lines of credit are unsecured or based primarily on revenue.

    What industries commonly use nationwide expansion financing?

    Retail, restaurants, healthcare practices, construction, logistics, and professional services frequently use nationwide expansion financing to open locations or purchase equipment. Seasonal businesses also use it to build inventory ahead of peak demand.

    How do I choose the best lender for business expansion loans nationwide?

    Compare funding speed, total repayment cost, and transparency of terms across at least two or three lenders before deciding. Prioritize lenders willing to clearly explain fees and repayment schedules before any documents are signed.

    Final Thoughts

    Business expansion loans nationwide give business owners a practical way to fund growth without being limited by their local banking market. Whether the goal is opening a new location, purchasing equipment, or building working capital ahead of a busy season, matching the right loan type to the right timeline makes the difference between a smooth expansion and a costly one.

    As a result, taking time to compare lenders, understand qualification requirements, and review repayment terms before signing is worth the extra effort. With the right nationwide lender and a clear expansion plan, growing a business across state lines no longer has to mean waiting months for capital.

  • Business Lines of Credit for Small Businesses: Guide

    Business Lines of Credit for Small Businesses: Guide

    Business Lines of Credit for Small Businesses: Guide

    Business lines of credit for small businesses give owners flexible, on-demand access to working capital without the rigid structure of a traditional term loan. Instead of receiving a lump sum upfront, a business draws funds as needed, repays what it uses, and can borrow again — making this financing tool especially useful for managing cash flow gaps, seasonal dips, or unexpected expenses. According to the Federal Reserve’s Small Business Credit Survey, lines of credit remain among the most commonly sought financing products for firms nationwide.

    In addition, because repayment terms are typically shorter and more flexible than a bank term loan, a revolving credit line often fits businesses that need quick access to cash rather than a large one-time investment. This guide explains how these credit lines work, what lenders look for, and how to apply with confidence.

    What Are Business Lines of Credit for Small Businesses?

    Business lines of credit for small businesses are revolving financing arrangements that let a company borrow up to a set limit, repay the balance, and borrow again as needed. Unlike a term loan, interest is charged only on the amount drawn — not the entire credit limit — which makes it a cost-efficient way to handle short-term needs.

    Consequently, a small business line of credit works similarly to a business credit card, except it usually offers higher limits and lower rates. Owners can tap the line whenever payroll, inventory, or an unexpected repair comes up, then pay it back on their own schedule within the lender’s terms.

    How Does a Small Business Line of Credit Work?

    A revolving credit for small businesses arrangement has two main phases: the draw period, when funds are available to withdraw, and the repayment period, when the borrowed amount is paid back with interest. As balances are repaid, the available credit replenishes, so the business can draw again without reapplying.

    Secured vs. Unsecured Options

    Secured lines require collateral, such as receivables, inventory, or equipment, and typically offer lower rates. Unsecured lines rely more heavily on revenue and personal credit history, so approval depends on cash flow strength rather than pledged assets. As explained on the Wikipedia entry on lines of credit, revolving credit structures are common across both consumer and commercial lending.

    Draw Fees and Maintenance Costs

    Some lenders charge a small draw fee each time funds are withdrawn, plus an annual or monthly maintenance fee to keep the line open. Reviewing these details closely, alongside the typical costs of a small business line of credit, helps owners avoid surprises later.

    Small business owner reviewing business lines of credit for small businesses on a laptop dashboard

    Business lines of credit for small businesses give owners a clear view of available funds at any time.

    Qualifying for a Working Capital Line of Credit

    Lenders generally evaluate a few core factors before approving a working capital line of credit: time in business, monthly revenue, and personal or business credit history. Most alternative lenders look for businesses generating at least $20,000 in monthly revenue and operating for six months or longer, while banks and SBA-backed programs often require two or more years in business.

    In particular, businesses with thin credit files can strengthen their application by providing clean bank statements and demonstrating consistent deposits. For a closer look at qualification thresholds, see this guide on how to qualify fast for small business working capital loans, which covers many of the same underwriting factors lenders use for credit lines.

    Step-by-Step: How to Apply for a Business Line of Credit

    Applying for a business credit line is straightforward when the paperwork is organized in advance. Below is the general process most lenders follow, from initial assessment through funding.

    1. Assess funding needs. Review recent cash flow patterns to determine how much revolving credit is actually needed and which expenses it should cover.
    2. Gather financial documentation. Collect recent bank statements, tax returns, a voided check, and identification so underwriting moves quickly.
    3. Compare lenders and offers. Evaluate credit limits, draw fees, repayment terms, and annualized costs across multiple lenders before choosing one.
    4. Submit the application. Complete the application accurately and upload documents so the lender can verify revenue and creditworthiness without delays.
    5. Review terms before signing. Read the draw period, repayment schedule, and personal guarantee requirements carefully before accepting the offer.
    6. Draw funds and manage repayment. Draw only what is needed, track repayment deadlines, and repay promptly to keep the line available.
    For a more detailed walkthrough of each stage, this step-by-step guide to getting a small business line of credit breaks down documentation requirements lender by lender. Businesses can also review options directly through USA Patriot Loans, which works with established businesses nationwide seeking $30,000 to $20 million in financing.

    Business Line of Credit vs. Term Loan: Which Fits Your Business?

    Choosing between a revolving line and a term loan depends largely on how the funds will be used. A line of credit suits ongoing or unpredictable expenses, while a term loan works better for a single, defined purchase like equipment or expansion.

    Feature Line of Credit Term Loan
    Funding structure Revolving, draw as needed Lump sum, one-time
    Best for Cash flow gaps, emergencies Large, defined purchases
    Interest charged on Amount drawn only Full loan amount

    Therefore, many owners keep both tools available: a term loan for planned growth and a credit line for flexibility. This comparison of choosing between a business line of credit and a term loan walks through additional scenarios in more depth.

    Typical Costs for a Small Business Line of Credit

    Costs vary widely depending on the lender, the business’s credit profile, and whether the line is secured. Annualized rates can range from single digits for bank-backed lines to significantly higher for short-term alternative products. Because interest applies only to what is drawn, businesses that borrow conservatively often pay far less than the stated maximum rate.

    In contrast to a fixed-rate term loan, a credit line’s total cost depends on usage patterns, so two businesses with the same limit can end up paying very different amounts. For a full cost breakdown, see how much a small business line of credit typically costs, and consult the U.S. Small Business Administration’s loan program overview for government-backed alternatives.

    Common Mistakes to Avoid With a Business Credit Line

    Above all, avoid drawing the maximum limit immediately just because it is available. Overdrawing early reduces flexibility for genuine emergencies later and increases repayment pressure.
    Similarly, using a revolving line for long-term investments — such as buying property or heavy equipment — often costs more than a term loan designed for that purpose. Instead, match the financing tool to the timeline of the expense, and if fast approval matters most, compare options through this list of small business loans with fast approval and minimal paperwork.

    Business owner preparing documents to apply for a small business line of credit

    Organized documentation speeds up approval for business lines of credit for small businesses.

    Frequently Asked Questions About Business Lines of Credit for Small Businesses

    What are business lines of credit for small businesses?

    Business lines of credit for small businesses are revolving financing arrangements that let a company borrow up to a set limit, repay what it uses, and borrow again as needed. Interest applies only to the drawn balance, not the full limit, which keeps costs proportional to actual use.

    How does a business line of credit differ from a term loan?

    A term loan provides one lump sum repaid on a fixed schedule, while a line of credit is revolving and can be drawn from repeatedly. Lines of credit suit ongoing needs, whereas term loans fit a single, defined purchase.

    How much funding can a small business get with a line of credit?

    Credit limits typically range from $10,000 to $500,000, though some lenders extend larger facilities for established, high-revenue businesses. The exact amount depends on annual revenue, time in business, and credit history.

    How long does it take to get approved for a business line of credit?

    Online and alternative lenders can approve and fund a line within one to three business days. Bank and SBA-backed lines usually take several weeks due to more extensive underwriting.

    What credit score is needed to qualify for a business line of credit?

    Most alternative lenders accept personal credit scores of 600 or higher, while banks typically prefer 680 or above. Lower scores may still qualify but often come with higher rates or smaller limits.

    Are business lines of credit secured or unsecured?

    Both structures exist. Secured lines require collateral and often carry lower rates, while unsecured lines rely on creditworthiness and revenue history instead of pledged assets.

    How much does a small business line of credit cost?

    Costs vary by lender and risk profile, generally ranging from single digits to significantly higher annualized rates depending on structure and fees. Only the amount drawn accrues interest.

    Can a startup qualify for a business line of credit?

    Startups with limited history sometimes qualify through lenders focused on personal credit or projected revenue, but most alternative lenders prefer at least six months to one year of operations with steady monthly revenue.

    What is the difference between a line of credit and a merchant cash advance?

    A line of credit is a revolving loan repaid on flexible terms, while a merchant cash advance is a lump-sum advance repaid through a fixed percentage of daily sales. Lines of credit are generally more predictable and less costly over time.

    What documents are required to apply for a business line of credit?

    Lenders typically request recent business bank statements, tax returns, identification, and a voided business check. Some also ask for a profit and loss statement or accounts receivable aging report.

    What are common mistakes business owners make with a line of credit?

    Common mistakes include drawing the maximum amount immediately, ignoring repayment terms, and using the line for long-term investments better suited to a term loan.

    Can a business line of credit be used for any business expense?

    Most lenders allow broad use, including payroll, inventory, supplies, and short-term cash flow gaps. Some restrict use for real estate purchases or refinancing other debt, so it helps to confirm allowed uses beforehand.

    How do draw periods and repayment periods work?

    During the draw period, a business can access funds up to its limit as needed. Once drawn, repayment usually begins on a weekly, biweekly, or monthly schedule until the balance clears and available credit is restored.

    Is a personal guarantee required for a business line of credit?

    Most lenders require a personal guarantee, especially for unsecured lines or newer businesses. This means the owner is personally responsible for repayment if the business cannot cover the balance.

    What happens if a business does not use its full credit line?

    Unused credit generally does not accrue interest, though some lenders charge a small maintenance or unused-line fee. Businesses can keep the line open for emergencies without any cost beyond that fee.

    Small business owner finalizing approval for a business line of credit with a lender

    Choosing the right lender makes securing a business line of credit for small businesses faster and simpler.

    Final Thoughts on Business Lines of Credit for Small Businesses

    In summary, business lines of credit for small businesses offer a flexible way to manage cash flow, cover emergencies, and bridge revenue gaps without committing to a fixed loan structure. Because interest applies only to what is drawn, this financing tool can be more cost-effective than a lump-sum loan when needs fluctuate month to month.

    Ultimately, the right choice depends on how the funds will be used, how quickly capital is needed, and how the business’s revenue and credit profile line up with lender requirements. Businesses ready to explore options, including through USA Patriot Loans, can compare terms, gather documentation, and move toward funding with a clearer sense of what to expect.

  • Invoice Financing Solutions for Small Business Cash Flow

    Invoice Financing Solutions for Small Business Cash Flow

    Invoice Financing Solutions for Small Business Cash Flow

    Invoice financing solutions give business owners a way to convert unpaid customer invoices into immediate working capital, rather than waiting 30, 60, or even 90 days for payment. For many small and mid-sized companies, that gap between billing and collection creates real cash flow strain. Payroll comes due, suppliers need payment, and growth opportunities slip away while cash sits locked in receivables. In this guide, we break down how these funding tools work, what they cost, and how they compare to options like a business line of credit or revenue-based financing.

    Direct answer: Invoice financing solutions convert unpaid invoices into fast cash by advancing 80% to 90% of the invoice value upfront, with the balance released once the customer pays. It’s one of the quickest ways to fix a cash flow gap without taking on a traditional term loan.

    Business owner reviewing invoice financing solutions on a laptop in a small office

    Reviewing outstanding invoices is the first step toward finding the right invoice financing solutions for your business.

    What Are Invoice Financing Solutions?

    Invoice financing solutions are financial products that let a business borrow money against the value of its outstanding invoices. Instead of waiting for a customer to pay, the business receives most of that cash right away. Consequently, day-to-day operations don’t have to pause while receivables sit on the books.

    This category falls under the broader umbrella of accounts receivable financing, a term used by Investopedia to describe any funding secured by unpaid customer bills. Two common structures exist: invoice factoring, where the lender takes over collections, and invoice discounting, where the business keeps managing its own customer relationships. Both approaches aim to close the same gap—cash tied up in receivables that haven’t converted to available funds yet.

    How Invoice Financing Solutions Work

    In practice, the process is straightforward. A lender evaluates the invoice, the paying customer’s payment history, and the business’s receivables aging report. Once approved, funds typically move fast, often within one to three business days. As a result, businesses gain flexibility that traditional term loans usually can’t match on speed alone.

    Here is the typical step-by-step flow:

    1. Submit outstanding invoices from creditworthy business customers to the lender for review, along with basic financials to verify accounts receivable value and customer payment history.
    2. Receive an advance once approved—the lender typically wires 80% to 90% of the invoice value directly into your business bank account within one to three business days.
    3. Your customer pays the invoice on its original terms, either to the lender under factoring or to your business under invoice discounting, depending on the structure chosen.
    4. After the invoice clears in full, the lender releases the remaining reserve balance minus fees, completing the cycle and freeing that receivable for future funding.

    Types of Invoice Financing Solutions to Consider

    Not every business needs the same structure. Spot factoring lets a company finance a single invoice or a handful of them, which works well for occasional cash gaps. Whole-ledger agreements, on the other hand, finance the entire receivables portfolio and often carry lower per-invoice fees in exchange for volume commitment.

    Recourse financing means the business remains responsible if a customer fails to pay, while non-recourse financing shifts more of that risk to the lender—usually at a higher cost. Meanwhile, businesses with heavy equipment needs alongside receivables gaps sometimes pair invoice funding with equipment financing to cover both fronts at once.

    Hands organizing unpaid invoices as part of accounts receivable financing process

    Sorting invoices by customer and due date helps determine which accounts qualify for financing.

    Invoice Financing vs. Other Business Funding Options

    Invoice financing is not the only path to working capital, so it helps to see how it stacks up. A business line of credit offers revolving access to funds but usually requires stronger credit and collateral than invoice financing does. In contrast, invoice financing leans on your customers’ payment reliability rather than your personal credit score.

    Similarly, revenue-based financing repays a lender through a percentage of ongoing sales, which suits businesses without large unpaid invoices but steady revenue instead. For companies that need funds across multiple categories—payroll, inventory, or equipment—it’s often worth comparing quick funding options for equipment and payroll before committing to one structure.

    Finally, businesses that need capital in under two days sometimes explore fast business funding delivered in 24 to 48 hours, which can complement or substitute invoice financing depending on urgency.

    What Do Invoice Financing Solutions Cost?

    Cost is usually the first question business owners ask, and understandably so. Fees typically range from 1% to 5% of the invoice value per month, according to industry data referenced by the U.S. Small Business Administration on accounts receivable-based financing. The final rate depends on customer creditworthiness, invoice size, and how quickly the invoice is expected to be paid.

    For example, a $50,000 invoice financed at a 3% monthly fee that takes 45 days to collect might cost roughly $2,250 in total fees. That’s often still cheaper than the cost of a missed early-payment discount from a supplier or a bounced payroll run, which is why many businesses view the fee as a manageable trade-off rather than a burden.

    Who Benefits Most from Invoice Funding?

    Businesses that invoice other businesses on net-30 to net-90 terms tend to benefit most from these arrangements. Staffing agencies, trucking companies, manufacturers, wholesalers, and government contractors are frequent users because their payment cycles are long but predictable. In addition, seasonal businesses appreciate that funding scales up automatically during high-invoice months and tapers off during slower stretches, unlike a fixed monthly loan payment.
    Choosing the Right Invoice Funding Partner

    Because terms vary widely between lenders, it pays to compare advance rates, fee structures, and whether the arrangement is recourse or non-recourse before signing. Above all, look for transparency—reputable lenders explain fees in plain language rather than burying them in fine print.

    USA Patriot Loans, a disabled-veteran-owned nationwide lending company founded in 2023, works with established businesses generating at least $20,000 in monthly revenue to arrange funding from $30,000 up to $20 million, including invoice financing alongside working capital loans, business lines of credit, and equipment financing. Businesses exploring their options can also review this guide to getting business financing funded fast for a broader comparison of funding paths.

    Business owner and lender finalizing an invoice financing solutions agreement

    Choosing a transparent lender is key to getting fair terms on invoice financing solutions.

    Frequently Asked Questions About Invoice Financing Solutions

    What are invoice financing solutions?

    Invoice financing solutions let a business borrow against unpaid customer invoices, typically receiving 80% to 90% of the invoice value upfront. The remaining balance, minus fees, is released once the customer pays.

    How does invoice financing differ from invoice factoring?

    Invoice discounting lets the business keep control of collections and customer relationships, while factoring transfers collection duties to the lender. Both fall under the broader category of accounts receivable financing.

    How fast can I get funded with invoice financing?

    Most lenders fund approved invoices within one to three business days after submission. Ongoing facilities can advance funds even faster once the account is established.

    What credit score do I need for invoice financing?

    Invoice financing focuses more on your customers’ creditworthiness than your personal credit score. Many lenders approve businesses with limited or fair credit history as long as invoices come from reliable, paying customers.

    What does invoice financing cost?

    Fees typically range from 1% to 5% of the invoice value per month, depending on customer risk and invoice volume. Total cost depends on how long the invoice remains outstanding before payment.

    Can startups use invoice financing solutions?

    Yes, startups with business-to-business invoices and creditworthy customers often qualify for invoice financing solutions even without years of operating history. Lenders weigh customer payment reliability more heavily than company age.

    What is the difference between invoice financing and a business line of credit?

    Invoice financing is tied directly to specific unpaid invoices, while a business line of credit is a revolving fund not linked to receivables. Lines of credit often require stronger credit history and collateral.

    Do I need to have all my customers approved for invoice financing?

    No, most lenders allow you to select specific invoices or customers to finance rather than your entire ledger. This flexibility is often called spot factoring.

    What industries use invoice financing the most?

    Staffing agencies, trucking companies, manufacturers, wholesalers, and government contractors commonly rely on invoice financing due to long payment cycles. Any business that invoices other businesses on net-30 to net-90 terms can typically qualify.

    Is invoice financing considered debt?

    Invoice financing is generally structured as an advance against an asset you already own rather than a traditional loan, so it does not always appear as long-term debt on your balance sheet. However, terms vary by lender and structure.

    What documents do I need to apply for invoice financing?

    Lenders usually request an accounts receivable aging report, recent bank statements, a list of customers being invoiced, and basic business formation documents. Some also review your customers’ payment history.

    Can I choose which invoices to finance?

    In most spot-factoring arrangements, yes, you can select individual invoices rather than committing your whole receivables ledger. Whole-ledger agreements exist too, usually at lower per-invoice fees.

    What happens if my customer doesn’t pay the invoice?

    In recourse financing, the business remains responsible for repaying the advance if the customer defaults. Non-recourse agreements shift more of that risk to the lender, usually at a higher fee.

    How much of my invoice value can I access upfront?

    Most invoice financing solutions advance between 80% and 90% of the invoice’s face value upfront. The remaining reserve is paid out once the customer settles the invoice in full.

    Are invoice financing solutions a good fit for seasonal businesses?

    Yes, because funding scales with invoice volume, seasonal businesses can draw more capital during peak billing periods and less during slower months. This flexibility makes it different from fixed-payment term loans.

    Final Thoughts on Invoice Financing Solutions

    In summary, invoice financing solutions offer a practical way to unlock cash that’s already earned but not yet collected. Rather than waiting weeks or months for customer payments, businesses can access most of that value within days and keep operations running smoothly. Of course, the right choice depends on your invoice volume, customer reliability, and how the fees compare to alternatives like a line of credit or term loan.

    Ultimately, comparing multiple funding paths—including options detailed at USA Patriot Loans—helps ensure you choose the structure that fits your cash flow cycle rather than forcing your business into a one-size-fits-all product. For businesses juggling payroll, inventory, and growth all at once, invoice financing solutions can be the difference between stalling and staying in motion.

  • Revenue Based Financing Options for Small Business Growth

    Revenue Based Financing Options for Small Business Growth

    Revenue Based Financing Options for Small Business Growth

    Revenue based financing options give small business owners a way to access capital by repaying a lender with a fixed percentage of future sales instead of a fixed monthly payment. For many founders, this approach feels less rigid than a traditional bank loan, especially when cash flow varies from month to month. In this guide, we’ll break down how revenue-based funding works, who it fits best, and how it compares to other tools like bank loans with fixed interest rates. We’ll also walk through the qualification steps so you can decide whether this financing path suits your business today.

    Quick Answer: Revenue based financing options let a business trade a percentage of future monthly revenue for upfront capital, with no fixed payment amount and repayment that flexes alongside sales.

    What Is Revenue Based Financing?

    Revenue based financing options are funding tools that provide a lump sum of capital in exchange for a fixed percentage of a business’s future monthly revenue, continuing until the total repayment amount is satisfied. Unlike a conventional term loan, there is no set monthly installment. Instead, payments rise during strong sales months and shrink during slower ones.

    This structure is why many owners describe it as a flexible alternative to a fixed-payment loan. Because the lender’s repayment is tied directly to revenue performance, the underwriting process leans heavily on bank statements and sales history rather than personal credit alone. As a result, businesses with strong cash flow but limited collateral often qualify more easily than they would through a bank. You can read more about this structure in the Wikipedia overview of revenue-based financing.

    Small business owner reviewing revenue based financing options on a laptop chart

    Reviewing monthly revenue is the first step to comparing revenue based financing options.

    How Does Revenue-Based Funding Work?

    In practice, a lender first calculates an advance amount based on your average monthly revenue over the past three to twelve months. Then, instead of charging traditional interest, the lender applies a factor rate — a multiplier such as 1.2 or 1.4 — to determine the total amount owed. For example, a $50,000 advance at a 1.3 factor rate means $65,000 must eventually be repaid.

    Repayment usually happens through automatic daily or weekly deductions from a business bank account or merchant processing account. Because the deduction is a percentage of revenue rather than a flat dollar figure, payments naturally adjust as sales fluctuate. Consequently, a slow month results in a smaller deduction, while a strong month speeds up repayment.

    Steps to Qualify for Revenue Based Financing Options

    1. Review your monthly revenue. Pull three to six months of bank statements and calculate your average monthly revenue, since this figure largely determines how much funding you can qualify for.
    2. Gather financial documentation. Collect bank statements, proof of business ownership, and recent tax returns so a lender can quickly verify revenue and history during underwriting.
    3. Compare revenue based financing options. Request quotes from more than one lender and compare the factor rate, total repayment, and the deduction percentage before choosing an offer.
    4. Submit your application. Complete the application with supporting documents and respond quickly to underwriting questions to keep the process moving.
    5. Receive funds and begin repayment. Once approved, funds typically arrive within one to three business days, and repayment starts automatically as a percentage of incoming revenue.

    Revenue Based Financing Options vs. Traditional Business Loans

    Traditional term loans and SBA loans generally offer lower overall costs, but they also require stronger credit, collateral, and longer approval timelines. In contrast, revenue based financing options prioritize speed and revenue consistency over credit history. This makes them appealing for businesses that need capital quickly or don’t yet qualify for bank-grade underwriting.

    However, this convenience typically comes at a higher cost. Therefore, it’s worth comparing the true cost of revenue-based funding against options such as a term loan with a fixed bank interest rate before committing. You can also review the U.S. Small Business Administration’s loan programs as a benchmark, since SBA-backed lenders approved more than $27 billion in 7(a) loans during fiscal year 2023, according to SBA figures.

    Types of Revenue Based Financing Options for Small Businesses

    Not every revenue-based product looks the same. In particular, businesses should understand a few common structures before comparing offers:

    • Merchant cash advances — repaid through a percentage of daily card sales, best suited to retail or restaurant businesses.
    • Bank-revenue advances — repaid through a percentage of total bank deposits, useful for service businesses with fewer card transactions.
    • Hybrid working capital loans — blend a fixed term with revenue-linked adjustments during slow seasons.

    Above all, the right structure depends on how your business collects revenue day to day. A business with heavy card sales may lean toward a merchant advance, while a service company billing clients by invoice might instead consider quick funding options built for payroll and equipment needs.

    Illustration comparing fixed loan payments against flexible revenue-based repayment percentages

    Comparing fixed loan payments against flexible revenue-based repayment helps clarify which financing fits best.

    Who Benefits Most From Revenue-Based Business Funding?

    Seasonal businesses, retailers, and service companies with variable monthly income tend to benefit the most, since payments scale with sales rather than staying fixed. Similarly, businesses that need capital quickly for inventory, payroll, or an unexpected expense often turn to revenue-based funding because approval can happen in days rather than weeks.

    On the other hand, businesses with strong credit and steady, predictable revenue may find better long-term value in a traditional term loan or a financing option designed specifically for equipment purchases. As always, the right fit depends on your specific revenue pattern and how urgently you need the funds. USA Patriot Loans, a disabled-veteran-owned lender founded in 2023, works with businesses nationwide generating at least $20,000 in monthly revenue to match owners with the financing structure that fits their cash flow.

    Costs, Factor Rates, and Repayment Terms

    Instead of an annual percentage rate, revenue-based funding typically uses a factor rate between roughly 1.1 and 1.5. For example, a $100,000 advance at a 1.3 factor rate requires $130,000 in total repayment, regardless of how long it takes. As a result, paying it off faster generally lowers the effective annualized cost, while a slow repayment period raises it.

    Because of this structure, it’s important to calculate the daily or weekly deduction amount before signing any agreement. In addition, always ask whether early payoff offers any discount, since not every lender provides one. For a deeper look at whether this cost structure makes sense for your situation, see this breakdown of whether revenue-based financing is a good option for your business.

    How to Choose the Right Revenue Based Financing Options

    First, calculate your true monthly cash flow after existing debt obligations, since this determines how much of a revenue deduction your business can comfortably absorb. Next, request itemized quotes from several lenders and compare the factor rate, total repayment figure, and deduction percentage side by side rather than focusing on the advance amount alone.

    Finally, consider pairing your search with related financing research, such as this guide to fast-approval small business loans with minimal paperwork. Businesses headquartered anywhere in the United States can also explore nationwide funding programs directly through USA Patriot Loans, which offers funding from $30,000 up to $20 million across working capital, equipment, and revenue-based products.

    Business owner and lender finalizing a revenue based financing agreement at a desk

    Comparing offers carefully helps ensure the chosen revenue based financing options match your cash flow.

    Frequently Asked Questions About Revenue Based Financing Options

    What are revenue based financing options?

    Revenue based financing options are funding arrangements where a business receives a lump sum of capital and repays it through a fixed percentage of monthly revenue until the agreed total is paid off. Payments rise and fall with sales, so there is no fixed installment like a traditional loan.

    How does revenue based financing work?

    A lender advances capital based on your historical revenue, then collects a set percentage of future sales through daily or weekly deductions. The total repayment amount is calculated using a factor rate rather than a traditional interest rate.

    Why do small businesses choose revenue-based funding?

    Businesses with seasonal or fluctuating income often prefer revenue-based funding because payments scale down during slower months. It also tends to have faster approval timelines and fewer collateral requirements than bank loans.

    How is revenue-based financing different from a business line of credit?

    A business line of credit lets you draw funds as needed and pay interest only on what you use, while revenue-based financing provides a lump sum repaid as a percentage of sales. Lines of credit are typically revolving, whereas revenue-based deals are usually one-time advances.

    What does revenue based financing cost?

    Costs are expressed as a factor rate, commonly between 1.1 and 1.5 times the amount borrowed, rather than an annual percentage rate. The effective cost depends heavily on how quickly the business repays the advance.

    How fast can I get approved for revenue based financing options?

    Many lenders can approve and fund revenue-based financing within 24 to 72 hours because underwriting relies primarily on bank statements and revenue history. Same-day funding is sometimes available for qualified applicants.

    What documents do I need to qualify?

    Most lenders request three to six months of business bank statements, proof of monthly revenue, and basic business identification documents. Tax returns and financial statements may be requested for larger funding amounts.

    What is a factor rate in revenue-based financing?

    A factor rate is a multiplier applied to the amount borrowed to determine total repayment, expressed as a decimal such as 1.2 or 1.4. Unlike an interest rate, it does not change based on repayment timing, though the effective annualized cost does.

    What common mistakes do business owners make with revenue-based funding?

    A frequent mistake is stacking multiple advances at once, which can strain daily cash flow across several repayment obligations. Another is failing to compare the total repayment cost across offers before signing.

    Is revenue-based financing better than a merchant cash advance?

    Revenue-based financing and merchant cash advances are structurally similar, but revenue-based deals often use total bank revenue rather than card sales alone. The better choice depends on how your business collects revenue day to day.

    What credit score is required for revenue based financing options?

    Credit score requirements are generally lower than bank loans, with many lenders approving applicants with scores in the mid-500s or higher. Revenue consistency typically matters more than credit history in underwriting decisions.

    Can startups qualify for revenue-based funding?

    Startups with little or no revenue history usually do not qualify, since lenders base offers on consistent monthly revenue. Most programs require at least six months to a year of operating history and a minimum monthly revenue threshold.

    What are the best practices before signing a revenue-based financing agreement?

    Always calculate the total repayment amount and the effective daily or weekly deduction before signing, and confirm there are no early payoff penalties. It also helps to compare at least two or three offers side by side.

    How much funding can my business get through revenue based financing options?

    Funding amounts typically range from a few thousand dollars up to several million, depending on monthly revenue and time in business. Lenders generally offer advances equal to a percentage of average monthly revenue.

    Final Thoughts

    Ultimately, revenue based financing options work best for businesses that need fast capital and prefer repayment that flexes with sales rather than staying fixed. Still, it’s worth weighing the total cost against alternatives like SBA loans, term loans, or a business line of credit before signing an agreement. By comparing factor rates, repayment percentages, and funding timelines across a few lenders, you can choose the structure that genuinely fits your cash flow. For businesses ready to move forward, resources like USA Patriot Loans and the SBA’s loan program directory are reasonable starting points for further research.

  • Term Loans for Expanding Businesses: A Complete Guide

    Term Loans for Expanding Businesses: A Complete Guide

    Term Loans for Expanding Businesses: A Complete Guide

    Term loans for expanding businesses give owners a lump sum of capital that gets repaid on a fixed schedule, making them one of the most predictable ways to fund growth. Whether you are opening a second location, hiring a sales team, or investing in new equipment, this type of financing hands you the working capital upfront and lets you plan around a steady monthly payment. For established companies ready to scale, that predictability often matters more than any other feature.

    Small business owner reviewing term loans for expanding businesses paperwork

    Reviewing financing options is the first step toward securing term loans for expanding businesses.

    What Are Term Loans for Expanding Businesses?

    Term loans for expanding businesses are lump-sum financing products repaid over a fixed period with regular installments. A lender approves a set amount based on revenue and credit, disburses it in one payment, and the borrower repays principal plus interest until the balance reaches zero.

    These loans differ from revolving credit because the full amount arrives upfront rather than being drawn as needed. As a result, business owners often choose term loans when they know the exact cost of an expansion project, such as building out a new location or purchasing equipment outright. In addition, repayment terms can range from six months to ten years or more, depending on the lender and loan program.

    How Business Term Loans Work

    Understanding the mechanics behind business term loans helps owners compare offers accurately. Lenders evaluate several factors before setting an approval amount, rate, and repayment schedule.

    Specifically, underwriters typically review monthly bank deposits, time in business, and personal or business credit history. Consequently, businesses with at least $20,000 in monthly revenue and six or more months of operating history tend to see the most competitive offers. Furthermore, once approved, funds often arrive within one to three business days for alternative lenders, though bank and SBA-backed loans usually take longer due to additional documentation requirements.

    Because payments are fixed, owners can build the expense directly into their monthly budget without worrying about fluctuating rates. This structure is one reason term loans remain a popular choice for planned growth rather than emergency cash flow gaps.

    Financial advisor explaining a business term loan agreement to a company owner

    A clear repayment plan is one reason growing companies rely on business term loans.

    Key Benefits of Growth Financing for Established Companies

    Growth financing gives owners more than just cash; it provides structure and predictability that supports long-term planning. Several advantages stand out for companies ready to scale.

    • Predictable payments: Fixed monthly installments make budgeting straightforward, unlike variable-payment products.
    • Larger funding amounts: Many programs support financing from $30,000 up to $20 million, covering major expansion projects.
    • Ownership retention: Unlike equity investment, a term loan does not require giving up any share of the company.
    • Flexible use of funds: Proceeds can cover equipment, inventory, hiring, renovations, or new locations without restriction.

    Above all, this combination of flexibility and predictability explains why term loans remain a preferred financing route for companies in an active growth phase.

    Term Loans vs. Other Business Financing Options

    Term loans are not the only path to expansion capital, so it helps to see how they compare against other common products. For instance, a business line of credit offers revolving access to funds, which suits ongoing or unpredictable expenses better than a lump-sum loan.

    Similarly, revenue-based financing ties repayment to a percentage of monthly sales, which can be helpful for seasonal businesses but often costs more over time than a fixed-rate term loan. In contrast, if your expansion involves purchasing machinery or vehicles, it may be worth reviewing equipment financing options that use the asset itself as collateral.

    According to the Federal Reserve’s Small Business Credit Survey, a large share of small firms that seek financing do so specifically to expand operations or pursue new opportunities, underscoring how common growth-driven borrowing has become among established companies.

    How to Qualify for a Business Term Loan

    Qualifying for term loans for expanding businesses becomes easier when owners prepare in advance. The following steps outline a practical approach.

    1. Calculate the exact amount needed for the expansion, including equipment, inventory, staffing, or leasehold improvements, so you request an appropriate loan size.
    2. Gather recent bank statements, tax returns, and profit and loss statements, then correct any errors before a lender reviews your application.
    3. Confirm your personal and business credit scores along with monthly revenue trends, since lenders weigh both factors heavily during underwriting decisions.
    4. Request quotes from banks, SBA lenders, and alternative financing companies, comparing rates, terms, fees, and funding speed before choosing one option.
    5. Complete the application accurately, upload requested documents promptly, and respond fast to underwriter questions to avoid delays in receiving your funds.

    Notably, businesses that skip preparation often face delays or denials simply because documentation was incomplete, not because they were unqualified.

    How Much Can You Borrow for Business Expansion?

    Loan amounts for expansion financing vary considerably based on the lender, program, and borrower profile. Generally, alternative lenders fund anywhere from $30,000 to a few million dollars quickly, while SBA-backed and bank term loans can reach as high as $20 million for well-qualified applicants.

    For context, the U.S. Small Business Administration guarantees billions of dollars in 7(a) loans annually, helping smaller companies access financing amounts that traditional banks might otherwise consider too risky. This guarantee often translates into more favorable rates and longer repayment terms for qualifying businesses.

    In addition, the amount you can borrow typically scales with monthly revenue. Lenders commonly cap loan size at a multiple of average monthly deposits, so businesses with stronger, more consistent cash flow generally qualify for larger amounts.

    Choosing the Right Lender for Expansion Financing

    Selecting a lender matters just as much as choosing the right loan structure. Therefore, business owners should weigh funding speed, total cost, and customer support before signing an agreement.

    For example, a bank might offer the lowest rate but take six to eight weeks to fund, which could delay time-sensitive expansion plans. On the other hand, an alternative lender may fund within days, which suits businesses that need to act quickly on a lease deadline or a limited-time equipment discount. If speed and paperwork simplicity matter most, it is worth reviewing options for fast-approval small business loans before committing to a longer bank process.

    According to the definition provided by Wikipedia’s overview of term loans, these products are typically used for capital expenditures or business expansion rather than day-to-day operating costs, which reinforces why matching the loan to a specific growth goal produces the best outcome. Companies such as USA Patriot Loans work with established businesses nationwide to structure financing that fits both the expansion timeline and repayment capacity.

    Retail storefront renovation funded through a term loan for business expansion

    Expansion financing often funds visible growth, from renovations to new storefronts.

    Frequently Asked Questions About Term Loans for Expanding Businesses

    What are term loans for expanding businesses?

    Term loans for expanding businesses are lump-sum financing products that a company repays over a fixed schedule, typically with a set interest rate and monthly payment. Business owners use them to fund growth projects like new locations, equipment, or hiring without giving up equity.

    How do term loans for expanding businesses work?

    A lender approves a fixed amount based on revenue, credit, and time in business, then disburses the funds in one payment. The borrower repays principal plus interest over weekly, biweekly, or monthly installments until the balance is paid off.

    How much can I borrow with a business term loan?

    Loan amounts generally range from $30,000 to $20 million, depending on revenue, collateral, and the lender’s program. Larger amounts usually require stronger financials and sometimes SBA backing.

    How long does it take to get approved for a term loan?

    Alternative and short-term lenders can approve and fund term loans in as little as 24 to 72 hours. Bank and SBA-backed term loans usually take two to eight weeks because of additional underwriting and documentation.

    What credit score do I need to qualify?

    Many alternative lenders approve applicants with credit scores in the mid-500s to 600s if revenue is strong. Traditional banks and SBA programs typically prefer scores of 650 or higher.

    What’s the difference between a term loan and a business line of credit?

    A term loan provides one lump sum with a fixed repayment schedule, while a line of credit offers revolving access to funds you draw and repay as needed. Term loans suit large, one-time expansion costs; lines of credit suit ongoing or unpredictable expenses.

    Are term loans better than merchant cash advances for expansion?

    Term loans generally cost less and offer predictable payments compared to merchant cash advances, which use factor rates and daily or weekly debits. For planned growth projects, a term loan is usually the more affordable option.

    What can term loan funds be used for?

    Business owners commonly use term loan proceeds for new locations, equipment purchases, inventory buildup, hiring, marketing pushes, or renovations. Lenders rarely restrict use as long as the purpose supports legitimate business operations.

    What are typical interest rates on business term loans?

    Rates vary widely, from single digits for SBA and bank term loans to higher rates for short-term alternative financing based on risk. Your rate depends on credit profile, revenue, time in business, and loan term length.

    What documents do lenders require for a term loan application?

    Most lenders request recent bank statements, tax returns, a profit and loss statement, and proof of business ownership. Some also ask for a business plan or collateral documentation for larger expansion loans.

    What mistakes should I avoid when applying for a term loan?

    Common mistakes include borrowing more than the expansion actually requires, ignoring the total cost of financing, and failing to compare multiple lenders. Applicants also hurt their approval odds by submitting incomplete financial documentation.

    Can startups qualify for term loans for expanding businesses?

    True startups with little revenue history often struggle to qualify, since most lenders require at least six months to a year in operation. Established businesses with consistent monthly revenue have far better approval odds.

    How long are repayment terms for business expansion loans?

    Repayment terms typically range from six months for short-term loans to 10 or more years for SBA and bank term loans. Longer terms lower monthly payments but increase total interest paid over time.

    Is collateral required for a business term loan?

    Some term loans require collateral such as equipment, real estate, or a blanket lien on business assets, while others are unsecured based on revenue and credit. Secured loans often come with lower rates and higher borrowing limits.

    Final Thoughts on Growing Your Business With a Term Loan

    In summary, term loans for expanding businesses remain one of the most reliable ways for established companies to fund growth without sacrificing ownership or flexibility. They offer predictable payments, sizable funding amounts, and terms that can be matched to the specific expansion project at hand. However, the right choice still depends on comparing rates, timelines, and lender requirements before signing an agreement.

    Ultimately, businesses that prepare their financials, define their funding needs clearly, and compare several lenders tend to secure better terms and faster approvals. If you are ready to explore financing for your next growth phase, visiting USA Patriot Loans is a practical next step toward finding a term loan structured around your business goals.